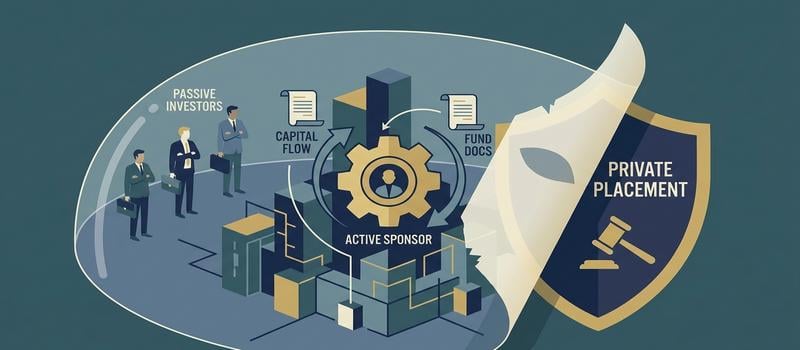
A real estate syndication is a deal where a sponsor raises money from investors to buy an asset, then runs it under agreed terms. The mechanics come down to three things: the entities that hold the risk, the fees the sponsor gets paid for doing the work, and the waterfall that decides who gets paid what and when. Get those three things right and the deal runs clean. Get them wrong and you end up with commingled liability, an undisclosed fee, or a promote that does not survive a tax audit.
This article walks through the actual structure, not the theory. Two entities, not one. Two standard fees, tied to work on the asset, not to the size of the raise. A waterfall that separates the preferred return from the promote. A Private Placement Memorandum that discloses the risk instead of pretending it does not exist. And a hard line around what counts as a broker-dealer problem versus what is just normal sponsor compensation.
Start with the entities. Every fee and every document in the rest of this article attaches to that structure.
The Structural Baseline: Why a Syndication Requires a Dual-LLC Setup
A safe syndication uses two separate entities: an Issuer LLC that holds the asset and takes in the investors, and a Manager LLC that runs the deal and collects the operational fees. One entity holds the risk of the asset. The other holds the risk of running it. You do not want those two things in the same box, and you never want either of them in your personal name.
This is the part people get wrong when they treat a syndication like a normal small business and form a single LLC for everything. A single-entity setup mixes investor money, sponsor liability, and operational decision-making into one pool. When something goes wrong, there is no wall between the problem and everyone standing next to it. The dual-LLC structure is the actual mechanics of syndicating real estate the right way, and it is the foundation every fee and every document in the rest of this article attaches to.
The Issuer LLC (The Investment Vehicle)
The Issuer LLC is where the investors put their money and where title to the property sits. Investors buy membership interests in this entity. That is the security they are purchasing. The Issuer holds the asset, receives the rents, pays the debt, and eventually distributes the profits.
This entity is almost always taxed as a partnership under Subchapter K. That matters for a specific reason: partnership taxation is what allows the special allocations you need to run a waterfall. If you form this entity as an S-corp because someone told you it saves on taxes, you break the ability to split economics the way a promote requires. More on that later, but flag it now.
The Issuer also does the work of containing liability at the asset level. If someone slips and falls at the property and sues, the claim runs against the entity that owns the property, not against the investors personally. An investor who wired in $100,000 has $100,000 at risk. Their house and their other assets are not on the table. That containment is a big part of why investors are willing to write the check.
The Manager LLC (The Sponsor’s Protection)
The Manager LLC is a separate entity that serves as the Managing Member of the Issuer LLC. It makes the decisions, signs the documents, and runs the business plan. It is also the entity that receives the operational sponsor fees.
The reason it is separate is protection. When you sign as the Manager LLC instead of signing personally, the decision-making liability lands on the entity, not on you. If an investor later claims the sponsor mismanaged the deal, the claim runs against the Manager LLC. Your personal assets sit behind another wall. Signing personally throws that wall away.
More sophisticated sponsors take the Manager side one step further and use a two-tier structure – a holding company that owns an operating company – to manage how their own compensation is taxed. One common approach splits the sponsor’s take into roughly 40% direct salary and 60% management fee, which reduces the payroll-tax bite on the fee portion. That is a tax-planning decision, not a securities-law requirement, and I would have your accountant confirm the split for your facts. But it is worth knowing the option exists before you set up a single flat entity and lock yourself out of it.
Standard Sponsor Fees: Getting Paid to Put the Deal Together
The sponsor gets paid through fees defined in the Operating Agreement and routed to the Manager LLC. The two most common are the Acquisition Fee and the Asset Management Fee. Both compensate work performed on the asset, not the act of raising money, and that distinction matters. I will come back to it.
The Acquisition Fee
The Acquisition Fee pays the sponsor for finding, underwriting, negotiating, and closing the deal.
That is real work. Somebody sourced the asset, ran the numbers, negotiated the purchase agreement, arranged the debt, and got it to closing. The Acquisition Fee is the compensation for that effort.
It is typically paid at closing, out of the raised capital or loan proceeds. A common range is 1% to 3% of the purchase price, though the number is negotiable and depends on the deal.
One thing to be clear about: the Acquisition Fee is tied to acquiring the asset, not to raising money. You are being paid because you bought and closed the deal, not because you brought in $2 million of investor capital. If the fee is really compensation for the raise dressed up as an acquisition fee, that is a different problem, and I will get to it in the broker-dealer section.
The Asset Management Fee
The Asset Management Fee is the ongoing fee paid to the Manager LLC for running the business of the investment after closing.
That means executing the business plan, communicating with investors, handling reporting and distributions, and overseeing whoever is managing the property day to day. It is the fee for keeping the deal on track over its life.
It is usually calculated one of two ways: as a percentage of gross revenues, or as a percentage of committed capital. A 1% to 2% figure is common. Which base you use changes the incentive, so pick it deliberately and state it plainly in the Operating Agreement.
Do not confuse asset management with property management. Asset management is overseeing the business of the investment – the strategy, the capital, the investors. Property management is overseeing the physical building – leasing units, fixing the roof, collecting rent. They are separate jobs, separate fees, and often separate people. If the sponsor is also going to collect a property management fee, that gets disclosed on its own.
The Role of Absolute Transparency
Here is the part that surprises a lot of sponsors: there is no SEC rulebook capping these fees.
You have real flexibility in how you structure the economics. You can set a high acquisition fee. You can layer in an asset management fee, a disposition fee, a refinance fee. You can build a split that leans heavily in the sponsor’s favor. None of that is illegal on its face.
What is not optional is disclosure. Every fee has to be spelled out clearly and explicitly so an investor knows exactly what the sponsor is taking and when. The risk is not the size of the fee. The risk is a fee an investor did not see coming.
So if a fee structure is legal and it is fully disclosed, whether it survives is a market question, not a securities-law question. Investors read the terms. If the fees are too rich for what you are offering, they walk, and you do not raise the money. That is a sales problem, not an SEC problem.
What we do not want is a fee that is buried, vague, or described one way in the pitch and another way in the documents. That is where disclosure failures turn into fraud claims. Set the fees where you want them, and then say so plainly.
The Economic Waterfall: Separating Preferred Returns from the Promote
The waterfall is the formula in the Operating Agreement that decides who gets paid, in what order, and how much. It has two moving parts most sponsors confuse: the preferred return that goes to the Limited Partners first, and the promote that rewards the General Partner on the backend.
None of this works like debt. Nobody in the waterfall is guaranteed anything. The waterfall just sets priority on cash that actually exists.
That distinction is where sponsors get into trouble, so let’s be precise about each piece.
The Preferred Return Is Not a Guarantee
A preferred return is a priority threshold. It gives the Limited Partners the first slice of available cash flow up to a stated rate – commonly 7% or 8% – before the sponsor participates in profits.
In plain English: the investors get paid first, up to that number. Only after they hit it does the money start splitting differently.
Here is the part that matters. A preferred return is an equity target, not a loan payment. If the property does not produce cash, you do not owe it the way you owe a lender.
Most deals structure the pref to accrue. If you distribute 5% in a lean year against an 8% pref, the missing 3% carries forward and has to be caught up later. But it accrues – it is not a debt you can be sued to pay on a fixed date.
So strip “guaranteed” out of your vocabulary and out of your investor materials. A preferred return describes payment priority, not a promise of return. If you tell investors 8% is guaranteed and the deal underperforms, you have handed them a fraud claim.
Return of Capital
Return of capital is the step where investors get their original principal back before the sponsor takes a large share of the profit.
The general rule: the Limited Partners receive 100% of their invested capital back before the promote kicks in on the bulk of the gains. You do not get to split the big upside until the investors are made whole on what they put in.
This usually happens at a capital event – a refinance that pulls cash out, or the sale of the asset. That is when there is real money to return, not just operating cash flow.
You can structure this in different orders. Some waterfalls return capital before the pref is fully satisfied; some after. The point is that the sponsor’s large backend participation sits behind the investors getting their money back.
The Promote (Carried Interest)
The promote is the sponsor’s disproportionate share of the backend profit, earned for executing the deal well. If investors put up nearly all the capital but the split above the pref is 70/30 in the sponsor’s favor, that extra 30% is the promote. It is also called carried interest.
The promote is not a fee. Fees like the acquisition fee and asset management fee get paid for doing work, whether the deal is a home run or a disappointment. The promote is purely performance-based – it only shows up if the deal produces profit above the hurdles.
That is the whole design. The sponsor’s real money is supposed to sit at the back of the line, behind the investors’ pref and return of capital.
One tax point that quietly destroys deals: the promote depends on the Issuer LLC being taxed as a partnership. A partnership can make “special allocations,” which is the mechanism that lets profit flow disproportionately to the sponsor after the hurdles are met.
If someone talks you into taxing the main Issuer entity as an S-corp – usually to save on self-employment tax – you lose that ability. An S-corp has to allocate profit strictly by ownership percentage. That kills the waterfall.
Save the S-corp conversation for the Manager entity if it fits. Keep the Issuer that holds the asset and the investors taxed as a partnership. If you do not, the promote you drafted on paper will not work the way the Operating Agreement says it should.
The Broker-Dealer Trap: Why You Cannot Charge a “Capital Raising Fee”
No, you cannot charge a fee based on how much money you raise. Transaction-based compensation for selling securities is broker-dealer activity, and doing it without a license violates Section 15(a) of the Securities Exchange Act.
The fees in the last section were tied to work on the asset. This fee is tied to the sale of the security, and that is a completely different regulatory animal.
The consequence is not a slap on the wrist. It puts your whole exemption at risk and can give investors a rescission right, meaning they can demand their money back if the deal goes sideways.
The Illusion of the Finder’s Fee
The myth is that you can take a 2% cut of the capital you bring in, or pay a friend a “finder’s fee” for introducing an investor who writes a check.
That is not allowed. The rule looks at what you are being paid for, not what you call it.
If your compensation moves up and down with the amount of money raised, that is transaction-based compensation. Anyone receiving it for selling securities has to be a registered broker-dealer.
Calling it a “consulting fee” or a “marketing fee” does not fix it if the payment is really tied to the raise. The SEC looks at substance, not the label on the invoice.
So the answer is simple. If you are not a licensed broker-dealer, you do not get paid a percentage of the raise, and you do not pay anyone else a percentage of the raise either.
Internal Compensation Adjustments
There is a real distinction here that sponsors miss. Partners and actual officers of the sponsor entity can adjust their internal equity splits based on what each person contributed to the deal.
The reason is that they are the issuer. The issuer is allowed to sell its own securities. If one partner did more of the fundraising work and the partners agree that person should get a larger slice of the promote, that is fine. That is an internal allocation among the people who own and run the deal.
Where sponsors get into trouble is paying people who are not real principals. Paying an assistant, a non-officer employee, or an outside consultant a cut tied to the money they brought in is an immediate red flag.
The problem is the transaction-based piece, not the fact that they helped. You can pay a salary. You can pay a flat fee for actual services. What you cannot do is pay them more because more money came in the door.
If someone is genuinely part of the sponsor, make them part of the sponsor – give them real equity and a real role. If they are not, do not pay them like a salesperson, because that is exactly what the rule is designed to catch.
The Legal Foundation: Why the Operating Agreement Needs the PPM
The Operating Agreement and the Private Placement Memorandum do different jobs. The Operating Agreement runs the math. The PPM discloses what happens when the math does not work out the way you projected.
You need both because securities law does not care how clean your economics are. It cares whether you told the investor the truth about the risks before they wrote the check.
The Operating Agreement (The Engine)
The Operating Agreement is the contract that wires the deal together and makes it run.
It binds the investors to the rules of the Issuer LLC, names the Manager LLC as the managing member, and gives the sponsor the authority to actually operate the deal. It is also the document that legally enforces everything covered earlier: the acquisition fee, the asset management fee, the preferred return, the return of capital, and the promote.
If the waterfall math lives anywhere, it lives here. When the sponsor takes a fee or a distribution, the Operating Agreement is the authority for doing it. Without it, there is nothing binding the investors to those terms, and nothing protecting the sponsor’s right to get paid.
The PPM (The Shield)
The Private Placement Memorandum is the disclosure record. Its job is to tell the investor everything that can go wrong.
The PPM lays out the risk factors, the conflicts of interest, and the plain reality that the investor can lose their entire principal. It says the preferred return is a target, not a promise. It discloses that the sponsor is being paid fees regardless of performance. It explains that the asset may not perform and the business plan may fail.
That disclosure is your protection. When an investment underperforms, unhappy investors go looking for something they were not told. The PPM is the record that says you told them.
Now the “required” question, because it gets stated too absolutely. Whether formal written disclosure is strictly mandated depends on the exemption you are using and who is in the deal. Under Rule 506(b), if you admit unaccredited investors, specific information delivery requirements attach. Under Rule 506(c), where every purchaser must be verified accredited, the formal delivery rules are lighter.
But “not strictly required” is not the same as “skip it.” Even when the exemption does not force a PPM on you, it is usually central to your disclosure record. The anti-fraud rules under Regulation D and the securities laws apply no matter which exemption you pick. If an investor claims you left out something material, the PPM is what you point to.
The Role of the Syndication Attorney
Assembling these documents to match your actual deal, not a template, is the job of an attorney providing legal services for real estate syndication sponsors.
The economics in your Operating Agreement have to reflect your specific splits: your fee structure, your preferred return, your promote, your tiers. The PPM has to describe your actual asset, your actual business plan, and the actual risks that come with them. A generic form does neither. It describes a deal that is not yours, which is worse than useless when a dispute comes.
The work is matching the paper to the deal. The waterfall in the Operating Agreement has to reconcile with the economics disclosed in the PPM, and both have to line up with what you actually told investors in the room. When those three things agree, the structure holds. When they do not, that gap is exactly where the problem starts.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.