Why the LLC vs. Corporation Debate is Already Settled
If you are choosing an entity to hold a real estate syndication, use a Manager-Managed LLC. That is the answer almost every time.
The reason is simple. An LLC gives you a liability shield similar to a corporation, but it passes income, losses, and depreciation through to the members instead of trapping them at the entity level. That combination is what makes real estate deal economics work.
Most of the “LLC vs. Corporation” content out there is written for someone starting a coffee shop, not someone raising capital from investors. For a syndication, the corporation options usually create tax problems you do not need. So let’s deal with why the corporate forms get eliminated, and then look at what the LLC actually gives you.
The Flaw of Double Taxation in C-Corporations
A C-Corporation is generally the wrong choice because it taxes the same dollars twice.
The corporation pays tax on its profits at the entity level. Then, when it distributes those profits to shareholders as dividends, the investors pay tax again on what they receive. For an income-producing asset, that second layer eats directly into the yield investors are counting on.
There is a second problem that matters just as much in real estate. Depreciation is one of the main tax benefits of owning real property, and in a C-Corp that depreciation stays trapped inside the corporation. It offsets the corporation’s income, but it never flows out to the investors’ individual returns.
That is why syndicators avoid holding the asset in a C-Corp. You lose the pass-through of both the income and the depreciation, and you hand a piece of the deal to the IRS twice.
The Rigidity of S-Corporations for Capital Raising
An S-Corporation fixes the double-tax problem but creates a different one: it does not scale for a capital raise.
S-Corps do offer pass-through taxation. The problem is the eligibility rules. An S-Corp is capped at 100 shareholders, the shareholders generally have to be individuals who are U.S. citizens or residents, and it can only have one class of stock.
A syndication routinely breaks all of those. You may want more investors than the cap allows, you may take in trusts, entities, or IRAs, and you almost always want more than one economic class between the sponsor and the investors. The S-Corp cannot hold that structure together.
There is a narrower use worth mentioning. Some sponsors, on advice from their CPA, elect S-Corp treatment for their separate management company – the entity that collects fees – for their own tax reasons. That is a conversation to have with your accountant. It is a different question from what holds title to the property, and the S-Corp is not the answer for the holding entity.
The Manager-Managed LLC Solution
The Manager-Managed LLC is the vehicle that fits. It avoids the double taxation of a C-Corp, it does not carry the shareholder restrictions of an S-Corp, and it still provides a liability shield at the entity level.
The word that matters here is “Manager-Managed.” An LLC comes in two flavors. In a Member-Managed LLC, every member has a say in running the company. That is fine for a solo operator or two partners flipping a house together.
A syndication needs the other flavor. In a Manager-Managed LLC, one party – the sponsor’s entity – runs the operation, and the investors come in as members without day-to-day control. That separation between the person operating the deal and the people funding it is exactly what a syndication requires, and it is why the Manager-Managed LLC is the default structure. How that separation actually works is the rest of this article.
The Operating Agreement is the Actual Financial Engine
Picking the LLC is the easy part. The Operating Agreement is where the actual deal lives.
The LLC is the outer shell. The Operating Agreement is the internal code that tells the shell how money moves, who controls what, and where the lines sit between the Manager and the Members.
If you form an LLC and stop there, you have a legal entity with no deal inside it. That is where a lot of first-time sponsors get into trouble.
Coding the Waterfall and Preferred Returns
Filing your articles of organization with the state does nothing to dictate how money is distributed. The state filing tells the world your LLC exists. It says nothing about who gets paid, in what order, or how much.
That all lives in the Operating Agreement.
The Operating Agreement is where you write the waterfall. That is the order in which cash flows out of the deal – typically a targeted preferred return to the limited partners first, then a split of the remaining profits between the general partner and the limited partners.
I use “targeted” for a reason. A preferred return is a priority of payment, not a promise of payment. The Operating Agreement can say the LPs are first in line for, say, an 8% preferred return, but nothing in that document guarantees the deal will generate the cash to pay it. Draft it that way, and disclose it that way.
The point is that the economics are engineered, not inherited. Two syndications can use identical LLCs and run completely different deals because their Operating Agreements are written differently.
Separating Control from Capital
The Operating Agreement is also where you separate control from capital.
The document explicitly grants day-to-day operational control to the Manager. The Manager decides how to run the asset, when to sell, whether to refinance, and how to handle the hundred smaller decisions that come up along the way.
The Members – the investors – do not get that control. They trade voting authority for limited liability and a passive position. That is the deal they are signing up for, and the Operating Agreement is what makes it real.
This structural separation is fundamental whether you are running a single-asset syndication or a fund. The model changes, but the Manager-versus-Member architecture in the governing document does not.
Matching the Entity to the Disclosures
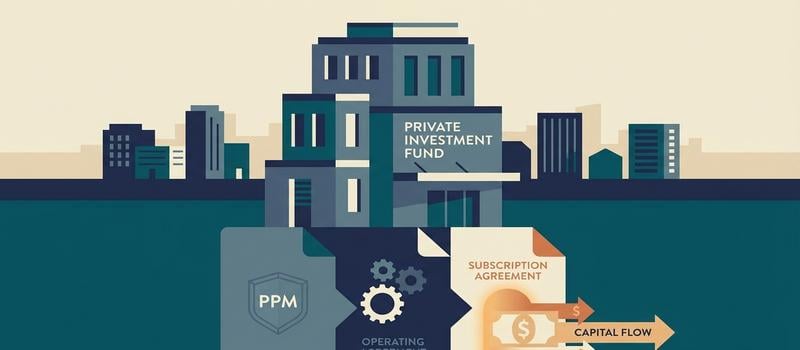
The Operating Agreement cannot contradict your Private Placement Memorandum. These two documents have to say the same thing.
The PPM is what you show investors. It explains and discloses the offering – the fees, the splits, the preferred return, the Manager’s authority. The Operating Agreement is the binding contract that governs the entity once the money is in.
If the PPM tells investors the Manager earns a 2% acquisition fee, but the Operating Agreement says 3%, you have a problem. Now you have disclosed one thing and contracted for another.
That is a liability problem and an operational problem at the same time. An investor can point to the mismatch and argue you misrepresented the deal, and your own governing document may not authorize the fee you told people you were charging.
So the fix is boring but essential: the numbers, the fees, and the waterfall in the Operating Agreement have to mirror the PPM exactly. Generic LLC formation does not get you there. The two documents have to be drafted together, by someone reading both at the same time.
The Standard Multi-Tier Architecture for Syndications
Most sponsors assume they form one LLC, put the property in it, and call it a day. That is not how experienced syndicators build it.
The standard structure uses at least two entities: an Issuer Entity that holds the asset and takes investor capital, and a separate Management Entity that runs the deal. The point of the separation is to keep the risks of one part of the structure from bleeding into the other.
The Issuer Entity (Property Holding LLC)
The Issuer Entity is the LLC that actually holds title to the real estate. It is also the entity your limited partners invest into, so when an investor wires capital, that money buys membership interests in the Issuer.
This entity is tied to one specific asset. You form a new one for each deal.
The reason is practical. If a tenant sues over an injury at Property A, you generally do not want that claim reaching the equity or operations of Property B. Keeping each asset in its own entity is a common way to limit that kind of cross-contamination, though how well it holds up still depends on the facts and on maintaining the entity properly.
The Management Entity (Sponsor LLC)
The Management Entity is the LLC through which the sponsor actually operates the deal. Sponsors rarely serve as manager of the Issuer in their personal name, and for good reason.
This entity is the Manager of the Issuer Entity. It holds the GP’s voting rights, it makes the operational decisions, and it typically collects the acquisition fee and asset management fee.
Putting the Management LLC between you and the deal creates a layer of separation between your personal affairs and the day-to-day operations. It does not make you personally untouchable – it is one structural layer, not a guarantee – but it is a meaningful part of how sponsors organize their risk.
Structuring this separation correctly is why operators retain legal services for real estate syndication sponsors rather than using generic filing websites. The filing is the easy part. Getting the two entities to line up with the Operating Agreement and the offering documents is the part that actually matters.
Housing Co-GPs and Joint Ventures
The Management LLC also gives you a clean place to house everyone on the sponsor side. Co-sponsors, capital raisers, guarantors, and joint venture partners can all sit as members inside the Management Entity.
This keeps the Issuer Entity’s cap table clean. Your investors see one Manager, not a tangle of individuals and side entities.
Behind that single Manager, the general partners can split their economics privately. If three sponsors are dividing the promote in some negotiated way, that arrangement lives inside the Management LLC’s own Operating Agreement, not in the documents your limited partners are reviewing.
That separation solves two problems at once. It simplifies the investor-facing structure, and it lets the sponsor group negotiate its internal deal without renegotiating anything with the investors.
How Entity Selection Connects to SEC Regulation D
The entity choice is not just a tax and liability question. It also affects whether your offering fits the securities exemption you are relying on. A properly drafted Manager-Managed LLC lines up with Regulation D because it keeps the investors passive, which is exactly what the exemption assumes.
Enforcing the Passivity Requirement
When you raise money under Regulation D, you are selling a security. The reason it is a security is that the investors are relying on your efforts to produce a return, not their own. They put in capital and step back. You run the deal.
That reliance is baked into the structure by using a Manager-Managed LLC. The Manager runs operations. The investor-members hold economic rights and limited voting rights, but they do not manage the venture.
A Member-Managed LLC muddies that. In a Member-Managed LLC, every member has a default operational voice. That is fine for two partners running an operating business together. It is a problem when you are selling interests to passive investors, because it undercuts the story that the investors are relying on the sponsor rather than themselves.
The issue is consistency. Your offering documents describe passive investors who rely on the sponsor. Your entity structure should say the same thing. A Member-Managed LLC contradicts that on its face.
Protecting the Reg D Exemption
The Manager-Managed structure gives you a clean, documented answer to the passivity question. On paper, control sits with the Manager, and the investor-members lack operational authority. That alignment between the entity, the Operating Agreement, and the offering materials is what you want if a regulator ever asks how the deal was run.
None of this guarantees the exemption. Whether your offering actually qualifies under Regulation D depends on the facts – how you sold it, who bought it, what you disclosed, and how you operated. But getting the entity structure right removes one avoidable inconsistency, and inconsistencies are where problems start.
If you want the mechanics of how the Manager-Managed architecture ties into the exemption, that is covered in more detail in our discussion of Reg D entity structure.
The practical takeaway is simple. Pick the entity form that matches the story your documents tell. In a Reg D raise, that story is passive investors relying on an active sponsor, and the Manager-Managed LLC is the structure that reflects it.
The Myth of the Absolute Liability Shield
Forming an LLC does not make a sponsor immune from personal liability. It gives you a layer of statutory protection, and that layer matters. But it is not a wall, and treating it like one is how sponsors get hurt.
The protection is real, but it is conditional. It depends on how the deal is financed and how you run the entity after formation.
The Reality of Lender Guarantees
Most commercial real estate lenders will not lend to a single-asset LLC on the strength of the entity alone. They want a warm body behind the loan.
That usually shows up as a personal guarantee or, in a non-recourse loan, a “bad-boy” carve-out guarantee. The bad-boy carve-out means the loan is non-recourse until the sponsor does something the lender carved out.
The carve-outs are not exotic. If the sponsor commits fraud, misapplies funds, diverts security deposits, or files an unauthorized bankruptcy to stall a foreclosure, the loan flips to recourse.
When that happens, the lender goes straight through the LLC to the sponsor’s personal assets. The entity does not stop it, because the sponsor signed a document that says the entity does not stop it.
So the LLC protects you from ordinary business risk. It does not protect you from your own signature on a guarantee.
Entity Maintenance and Veil Piercing
Liability protection also depends on how you operate the LLC after you file the articles of organization. Formation is the start of the protection, not the guarantee of it.
The most common way sponsors weaken the shield is commingling. If you pay personal expenses out of the syndication account, or move investor money in and out without documentation, you have blurred the line between yourself and the entity.
A plaintiff who sees that pattern will argue the LLC was never a real separate entity – that it was just you, operating under a different name. That argument is called piercing the corporate veil, and it can put your personal assets back on the table.
Keeping the veil intact is not complicated, but it is ongoing. Separate bank accounts. Clean records. The entity signs its own contracts. You treat the LLC as a distinct thing, because in court that is what you will need it to be.
The practical takeaway is simple. The LLC is a genuinely useful risk-management tool, but its effectiveness turns on execution and on the specific facts of your financing and your operations. Whether it protects you in any given situation depends on what you actually did, not on the fact that you filed the paperwork.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.