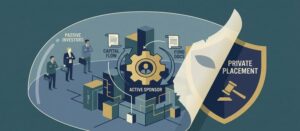
Real Estate Joint Ventures vs. Regulation D Syndications
Real estate joint ventures are not a substitute for a Regulation D syndication when capital partners are passive and rely on the sponsor’s efforts for profit.

Real estate joint ventures are not a substitute for a Regulation D syndication when capital partners are passive and rely on the sponsor’s efforts for profit.
Real estate development financing depends on Regulation D equity, lender subordination, and operating agreement terms that preserve senior debt priority.

A Syndication Is a Securities Offering, Not Just a Spreadsheet A real estate syndication is a securities offering. The sponsor is an issuer selling investment interests, and the moment you pool other people’s money to buy an asset you plan to manage, you are inside Regulation D whether you meant

The Blueprint: Connecting Entities to Economics A real estate syndication structure has two parts that have to work together: a legal chassis of layered entities, and an economic engine that moves the cash. The chassis is the set of entities that hold the asset, house the investors, and separate the
Table of Contents Introduction to Launching Real Estate Syndications Welcome to Launching Real Estate Syndications (You Are Here) The Real Estate Syndication Launchpad Syndication Founder’s Investment Theory Structuring Syndication Entities to Protect Yourself Finding Investors for Your Real Estate Syndication Finding Properties to Syndicate Making Money With Fees & Equity

A real estate syndication is a deal where a sponsor raises money from investors to buy an asset, then runs it under agreed terms. The mechanics come down to three things: the entities that hold the risk, the fees the sponsor gets paid for doing the work, and the waterfall

The Core Difference Between Syndication Fees and the Promote Sponsors get paid in two very different ways, and people constantly mix them up. Operational fees pay the sponsor for the work of running the business. The promote – also called carried interest – is the sponsor’s share of the upside,

The Difference Between a Legal Architect and a Document Typist A syndication attorney’s real job is structuring the deal, not producing paperwork. The documents come last. Before anyone drafts a Private Placement Memorandum, the attorney has to figure out how the mechanics of a real estate syndication or any other
How to Start a Real Estate Fund: The Legal Architecture A real estate fund is a securities offering. That is the part most sponsors skip past when they start thinking about a fund. They picture an entity, a waterfall, and a pitch deck, and they treat the legal work as

The Waterfall Is a Legal Framework, Not Just a Spreadsheet A distribution waterfall is the binding hierarchy written into your Operating Agreement that dictates how and when cash flows to the sponsor and the limited partners. It is a legal document, not a financial one. The spreadsheet describes what you