The Core Distinction: Legal Architecture vs. Distribution Channel
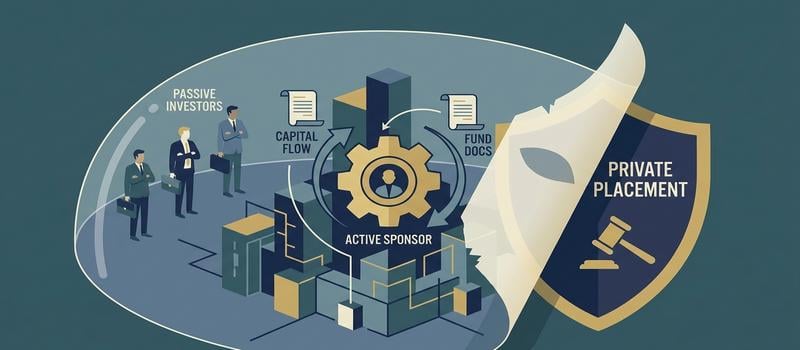
No, real estate crowdfunding and syndication are not two different asset classes. They are not even competing structures. A real estate syndication is the legal vehicle you use to pool investor capital. Crowdfunding is just a digital channel you use to market that vehicle.
Sponsors get this wrong all the time. They treat the decision as “crowdfunding or syndication,” as if they were choosing between two products on a shelf. That framing is backwards. The real decision is about which legal framework you build on and how much control you keep over the marketing.
Once you separate the container from the channel, the choices get a lot clearer.
Syndication Is the Legal Container
A syndication is the underlying legal mechanism for pooling investors into a single entity to acquire a specific asset. In practice, that entity is usually an LLC or an LP. The investors buy interests in that entity – the issuer – and the sponsor entity manages it.
That is the whole structure. The Operating Agreement or LPA defines who controls the deal and how the money gets split. The subscription documents control how investors come in. The PPM discloses the offering.
Here is the part sponsors miss. It does not matter where you find the investors. If you raise the money from ten people at a country club, that is a syndication. If you raise it from two hundred people who found you on the internet, that is still a syndication. The foundational legal container does not change based on the marketing channel.
Crowdfunding Is the Marketing Channel
“Crowdfunding” gets used loosely, and that is where the confusion starts. When most sponsors say crowdfunding, they mean advertising a deal online – running a public deal page, promoting it on social media, collecting soft commitments from a wide audience.
That colloquial use has nothing to do with the legal structure. It is a distribution method sitting on top of a syndication.
Legally, though, the word “crowdfunding” means something specific. True crowdfunding under the SEC’s rules triggers its own compliance regime – a registered third-party portal, distinct raise limits, and rules about who can invest and how much. That is a different animal from simply advertising a Regulation D deal online.
So when a sponsor tells me they want to “crowdfund” a deal, the first question is which one they mean. The answer determines which SEC exemption they are signing up for, and that changes everything downstream.
The Regulatory Divide: Regulation D vs. Regulation Crowdfunding (Reg CF)
The distinction between a legal container and a marketing channel becomes concrete when you look at which SEC exemption you are actually using. Traditional syndication runs on Regulation D. True legal crowdfunding runs on Regulation Crowdfunding (Reg CF) or Regulation A+.
Those are not interchangeable. They are different regulatory regimes with different limits, different investor rules, and different amounts of drag on your business.
So the real question is not “where does the money come from.” The real question is which exemption you are willing to comply with.
Why Regulation D Remains the Gold Standard
Regulation D is where the serious money is. Specifically, Rule 506(b) and Rule 506(c) account for something like 95% to 98% of all private placements. When a sponsor pools investors into an LLC or LP to buy an asset, this is almost always the exemption in play.
The reason is practical. Regulation D has no statutory cap on how much you can raise. If the deal needs $3 million, you raise $3 million. If it needs $80 million, the exemption still works.
It also keeps the framework clean. You prepare a Private Placement Memorandum, an Operating Agreement or LPA, and subscription documents. You file a Form D. You are not asking the SEC for permission or routing capital through a mandated third party.
That combination – unlimited ceiling, straightforward structure, sponsor control – is why Reg D is the default. It does not put you in a box.
The Frictional Reality of Reg CF
Regulation Crowdfunding is a different animal, and the friction shows up fast. The first problem is the cap. Reg CF limits you to $5 million raised over any rolling 12-month period. For most commercial real estate or private equity deals, that number is too small to matter.
The second problem is who shows up. Reg CF is built to let non-accredited retail investors participate, which sounds appealing until you run the deal. Instead of ten accredited investors writing $250,000 checks, you can end up with three hundred people writing $2,000 checks.
That is an administrative headache you do not need. Every one of those investors is on your cap table, every one gets K-1s, and every one can email you. The cost of servicing them is real, and it does not scale down.
The third problem is structural. Reg CF requires a registered funding portal and a set of ongoing disclosure obligations that most private equity and commercial real estate models were never designed to carry.
So for the typical sponsor, Reg CF is not a smaller version of Regulation D. It is a fundamentally different structure that fits a fundamentally different deal – usually an early-stage operating company raising a small round, not a syndication acquiring an asset.
Cap Table Control: Who Actually Owns Your Investor List?
If you raise capital through a crowdfunding portal, you usually do not own the relationship with the investors who funded your deal. The platform does.
That matters more than most sponsors realize when they sign up. The value in a syndication business is not just the current deal – it is the ability to bring the same investors into the next one. If you cannot do that, you are starting from zero every time.
The Mechanics of the Portal SPV
Most portals do not put your investors directly onto your cap table. They pool them into a Special Purpose Vehicle instead.
Here is what that looks like in practice. Say 100 investors each put money into a deal through a portal. Instead of those 100 names appearing as members of your issuer, the portal forms an SPV. All 100 investors buy into the SPV. The SPV then writes one check into your LLC.
Your cap table shows one investor: the SPV. The portal controls that SPV.
The practical result is that you rarely get direct access to the people actually funding your deal. You do not get their contact information. You do not build the relationship. The portal sits in the middle, and the portal intends to stay there.
That is not an accident. The SPV structure exists to protect the platform’s business model, not yours.
Anti-Circumvention Clauses and Deal Flow
Portals also protect that position contractually. Most platform agreements include a non-circumvention clause.
The clause does what it sounds like. If you met an investor through the portal, you cannot go around the portal to solicit that same investor for your next deal. You have to run the next raise back through the platform and pay the fees again.
So the investor you paid to acquire on Deal 1 is not really yours for Deal 2. You rented that investor. When you want them again, you pay rent again.
From your point of view, that is the core problem with the portal model. You are building the platform’s enterprise value, not your own. The investors you worked to attract stay on their books, behind their SPV, subject to their non-circumvent – and you keep paying to reach the same people.
Broker-Dealer Risk and the True Cost of Capital
Using a portal does not reduce your liability, and it usually does not save you money. You are still the issuer. That means you are still on the hook for the accuracy of the disclosures and the compliance of the offering, no matter who built the website or collected the checks.
The portal is not standing between you and the SEC. It is standing between you and your investors. That is a different thing.
The Danger of Unregistered Portals
The problem starts with how the platform gets paid. If a platform takes a percentage of the capital raised, that is transaction-based compensation, and transaction-based compensation is the classic hallmark of broker-dealer activity.
Section 15(a) of the Securities Exchange Act is the rule here. In plain English, if someone is in the business of effecting transactions in securities for compensation tied to those transactions, they generally need to be a registered broker-dealer.
A lot of tech platforms position themselves as software, or as a “listing service,” or as a passive marketing tool. But if they are taking a cut of the raise, the label does not matter. What matters is what they are actually doing.
If that platform is acting as an unregistered broker, it creates a problem you do not need. The SEC can take the position that the offering itself was tainted by the involvement of an unregistered broker. That exposes you, the issuer, to rescission risk, meaning investors could have the right to demand their money back.
You did not commit the registration violation. You just partnered with someone who did. And you are the one left holding the offering.
Permanent Platform Economics vs. Upfront Legal Fees
The economics also work against you over the life of the deal. A traditional syndication has real upfront cost. You pay legal fees to draft a compliant Private Placement Memorandum, an Operating Agreement, and the subscription documents. That is a fixed, one-time expense to build the container correctly.
A portal flips that into a variable, percentage-based cost. It often takes a percentage of the total raise, plus recurring administrative fees for as long as the investors are in the deal.
Run the math on a multi-million dollar raise. A percentage of the raise, compounded by ongoing admin fees, is almost always more expensive than the upfront cost of building your own documents. Getting the documents drafted correctly is a finite, one-time cost, and it is money well spent compared to a fee that never stops.
From your point of view, you are choosing between paying once to own the structure, or paying continuously to rent it. The rental almost always costs more, and it comes with the broker-dealer risk stacked on top.
Running Your Own Raise: The Rule 506(c) Alternative
You do not need a crowdfunding portal to advertise a deal online. Rule 506(c) under Regulation D already lets you do that. It permits general solicitation – public advertising – as long as every investor who actually buys is verified as accredited.
That is the path most sponsors are really looking for when they say they want to “crowdfund.” You get the marketing reach of the internet, and you keep the cap table, the investor relationships, and the enterprise value on your side of the table.
General Solicitation Under Reg D
Rule 506(c) is the exemption that lets you market in public. You can run a deal website, post about the offering on LinkedIn, host a webinar, and send it to a list you built yourself.
Under 506(b), you cannot do any of that. The general solicitation ban means the offering has to stay inside your existing network. 506(c) trades that limitation for a verification requirement, which I will get to in a second.
The advertising freedom is not a loophole. It is the actual design of the rule. The tradeoff is that the SEC wants tighter control over who ends up in the deal.
That is why the disclosure work matters more here, not less. When your offering is public-facing, the PPM, the operating agreement, and the marketing materials all have to say the same thing, and the risk factors have to hold up when a stranger reads the website cold. Drafting disclosures that support public marketing without contradicting the deal documents takes real legal attention, not a template you found online.
The Burden of Accredited Verification
Here is the tradeoff that makes 506(c) work. You cannot rely on the investor checking a box.
Under 506(b), an investor self-certifies. They tell you they are accredited, you have no reason to doubt it, and that is generally enough. Under 506(c), that is not enough.
The rule requires you to take reasonable steps to verify each investor’s accredited status. In practice that means reviewing tax returns, W-2s, bank and brokerage statements, or getting a written confirmation from the investor’s CPA, attorney, or a qualified third-party verification service.
That is real work, and it creates friction at the exact moment an investor is ready to write a check. Most sponsors handle it by outsourcing verification to a third party so they are not the ones collecting tax returns by email.
The verification burden is the price of admission for advertising in public. You accept it in exchange for reach and control. From your point of view, that is usually a better deal than renting a portal’s audience and losing the investor relationship entirely.
The Practical Decision: Build an Empire or Rent an Audience?
The choice comes down to what you are actually building. If you want a long-term enterprise where you own your investor relationships, structure your own syndication under Regulation D. If you only need to fund one deal and you do not care whether those investors ever come back, renting a portal might be an acceptable one-time expense.
Either way, you are the issuer. The legal liability for the offering sits with your entity, not the platform. Understand that before you decide the platform is doing you a favor.
Aligning the Legal Structure with the Business Goal
You remain the legal issuer whether you rent an audience or run your own raise. That fact does not change based on how you found the investors.
What changes is who owns the enterprise value afterward.
A clean cap table, direct control of your investor data, and the proven Reg D framework are how sustainable syndication businesses scale. When Deal 1 investors sit on your own LLC cap table, you can talk to them about Deal 2 without paying a toll. When they sit inside a portal’s SPV, you cannot.
That is the whole game. The individual raise matters less than whether you can compound the relationships across deals.
So before you solicit a dollar, get the architecture on paper. Decide whether you are running a 506(b) offering or a 506(c) offering, draft the Operating Agreement and PPM to match, and know exactly where your investors will appear on the cap table.
Building that framework correctly at the outset is usually a matter of working through the right legal services for real estate syndication sponsors before capital starts moving. Once the structure is on paper, you will know whether it actually fits what you are trying to build.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.