The Real Purpose of a Private Placement Memorandum
A private placement memorandum is your disclosure document. Its job is to tell an investor the material facts, the risks, the terms, and the mechanics of the deal – honestly and completely. It is not there to sell anyone on the opportunity.
That distinction matters more than most sponsors think. A PPM works as a liability shield precisely because it discloses. If a dispute comes later, the document you point to is the one that told the investor what could go wrong. A brochure does not do that. A disclosure document does.
So when a sponsor asks me what the PPM is supposed to accomplish in the raise, the honest answer is: it protects you by putting the truth on paper. It does not attract investors, and it does not make the money come in faster. That is a different job, and it belongs to a different document.
The Boundary Between Disclosing and Selling
The pitch deck sells. The PPM discloses. Keep those two jobs separate.
Your pitch deck is the marketing tool. It presents the vision, the strategy, and the economics you believe in. That is fine. That is what it is for.
The PPM does the opposite. It lays out the reality – the risks, the fees, the conflicts, the rules, and what happens if the deal does not perform the way you hope. It is supposed to be sober.
What we do not want is a PPM that reads like a sales pitch. When you fill the disclosure document with the same optimism that lives in the deck, you undercut the one thing the PPM is there to do. A risk section that soft-pedals the risks is not a shield. It is a liability. If an investor later claims you oversold the deal, a hyped-up PPM becomes the evidence against you.
If it were me, I would let the deck be enthusiastic and let the PPM be honest. Those are not in conflict. They are doing different jobs.
When SEC Rules Legally Mandate a PPM
No, a PPM is not strictly required by law for every Regulation D offering. But there is one point where it stops being a best practice and becomes a hard legal requirement: the moment you accept a single non-accredited investor under Rule 506(b).
That is the line. On one side, a PPM is a smart, protective choice. On the other side, SEC Rule 502(b) mandates specific disclosures, and a PPM is how you deliver them.
I still recommend a PPM on nearly every offering, even when the rule does not force one. I’ll explain why below, because the “all-accredited, so I don’t need a PPM” logic creates a trap that catches sponsors after the money is already in.
The Rule 506(b) Non-Accredited Investor Trigger
Rule 506(b) lets you accept up to 35 non-accredited investors, as long as each one is sophisticated enough to evaluate the deal.
The moment you accept even one of them, Rule 502(b) kicks in. That rule requires you to give non-accredited investors specific financial and non-financial disclosures, at a level roughly comparable to what a registered offering would provide. This includes audited or reviewed financials in many cases, plus a structured description of the business, the terms, and the risks.
In plain English: once a non-accredited investor is in the deal, you owe them a real disclosure document. The PPM is how you meet that obligation.
Skip it, and you have not just made a paperwork mistake. You have handed that investor a rescission right and a straightforward securities claim. If the deal goes sideways, they can argue you never gave them what the rule required, and they would be correct.
The Accredited Investor Liability Trap
The real danger in an all-accredited deal is not a missing checklist. It’s anti-fraud liability and a disclosure obligation that comes back retroactively the moment one investor’s accredited status falls through. Rule 506(c) offerings and all-accredited 506(b) offerings do not carry the Rule 502(b) disclosure list. There is no statutory checklist of documents you must hand over.
That is where sponsors get comfortable and decide to skip the PPM. The logic sounds fine: no rule requires it, everyone is accredited, so why spend the money.
Here is the problem with that logic. Your disclosure obligation does not disappear. It just shifts to the general anti-fraud rules under Rule 10b-5 and Section 17. Those rules apply to every offering, accredited or not. They say you cannot omit material facts or make misleading statements. A PPM is how you prove you disclosed the material facts.
Now add the accreditation risk on top of that. You built the whole deal on the assumption that every investor is accredited. Suppose one of them turns out not to be, whether because they lied on the questionnaire, their situation changed, or the verification was thin.
Without a PPM, you are trapped. You now have a non-accredited investor in a 506(b) deal, which triggers Rule 502(b) disclosure retroactively, and you have nothing to show you met it. You cannot go back in time and hand them the document you never wrote.
That is the practical reason to draft a PPM even when no rule forces you to. It is the cleanest defense you have when an investor sues after a deal underperforms. When they claim they were never told about a risk, you point to the section of the PPM where you told them.
You can run an all-accredited deal without a PPM. I just don’t think you’ll like the position it leaves you in if a single investor’s status is ever questioned.
The Core PPM Disclosure Checklist
A professional Regulation D PPM breaks down four things: the structure of the offering, the risks, exactly where the money goes, and the conflicts baked into how the sponsor gets paid. Miss any of these, and you have a document that describes the deal without actually protecting you.
Think of the sections below as the working checklist. Each one has a job. None of them are filler.
Executive Summary and Summary of Terms
This section states the hard facts of the offering up front. Offering size, minimum investment, unit price, and the specific exemption you are relying on – Rule 506(b) or Rule 506(c).
It also summarizes the core economics: the preferred return, the equity split, the waterfall. But summarizing is all this section does.
The actual economic terms live in the Operating Agreement. The PPM describes them so the investor understands the deal. The Operating Agreement is what makes them binding. If the summary here says one thing and the Operating Agreement says another, you have handed a plaintiff’s lawyer an argument. Keep them synchronized.
Risk Factors
The risk factors section is where a PPM earns its keep as a disclosure document. This is the part that protects you when a deal goes sideways and an investor claims they were never told it could.
The problem is that most sponsors treat this section as boilerplate. They copy a generic list of risks that could apply to any offering and move on. That is a mistake.
The risks have to match the actual asset and the actual structure. A debt fund carries interest rate risk and borrower default risk. A real estate deal carries tenant default, vacancy, and financing risk. An operating company carries execution risk, key-person risk, and competition. If your risk factors do not read like they were written for your specific venture, they are not doing their job.
Include the reliance-on-manager risk explicitly. Investors are passive. They have no operational control, no vote on day-to-day decisions, and no ability to remove you in most structures. Say that plainly. It is one of the most important disclosures in the entire document, because it is the reality of what the investor is signing up for.
Use of Proceeds and Sponsor Compensation
This section shows exactly where the money goes and exactly what you get paid. Both halves matter, and the second half is where sponsors get themselves in trouble.
On use of proceeds, show the actual deployment: acquisition costs, capital expenditures, legal and offering costs, operating reserves. An investor should be able to read this and understand what their dollar is buying.
On compensation, disclose every fee you take. Acquisition fees, asset management fees, disposition fees, refinancing fees, any promote or carried interest – all of it. If you are paying an affiliated entity, disclose that too.
The reason is simple. An undisclosed fee is not just bad form. It is a material omission, and a material omission about how the sponsor gets paid is the kind of thing that turns into a fraud claim. You do not lose anything by disclosing a fee an investor already expected. You lose everything by hiding one.
Management Team, Conflicts, and Tax Matters
This section covers who you are, where your interests diverge from the investors’, and the tax reality of holding the interest.
Start with factual bios and track records for the management team. Keep them accurate. This is disclosure, not a pitch, so resume inflation here is a real liability – not a marketing choice.
Then disclose the conflicts of interest, honestly. If the sponsor owns the property management company that the deal will hire, say so. If you are running other funds that compete for the same deals or your attention, say so. Conflicts are normal in syndication. You do not solve them by pretending they do not exist. You solve them by disclosing them clearly so the investor goes in with eyes open.
Finally, cover the baseline tax and ERISA points. Most syndication vehicles are pass-through entities, so the investor picks up their share of income and loss on a K-1 rather than the entity paying tax at the entity level. If you expect retirement-account money, address the ERISA and UBTI issues at least at a baseline level.
Two caveats. The PPM is not a tax opinion, and it should say so – the investor needs to consult their own advisor. And these disclosures still do not govern anything. The Operating Agreement controls management authority and the economic waterfall. The subscription documents control how the investor actually gets in. The PPM explains all of it; it does not replace any of it.
Integrating the PPM with the Complete Legal Architecture
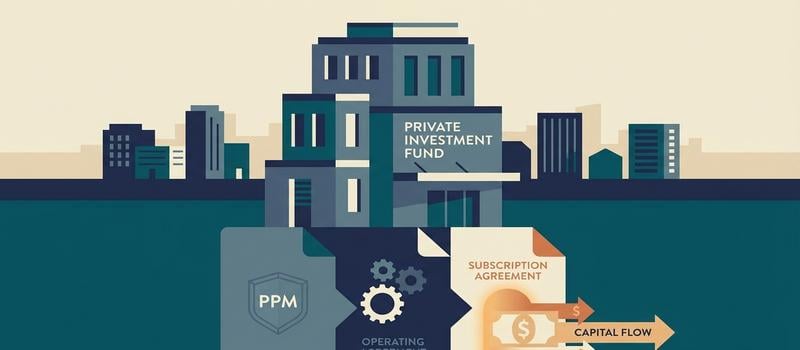
A Regulation D offering is not one document. It is a package: the PPM, the Operating Agreement or LPA, the Subscription Agreement, the Investor Questionnaire, and the regulatory filings – Form D and any state Blue Sky notices. Each piece has one job, and the protection only exists if all of them say the same thing. That is why we build the private placement memorandum legal package as a single, coordinated set of documents rather than drafting the PPM in isolation.
The PPM explains the offering. It does not govern the entity, admit the investor, or satisfy your filing obligations. The Operating Agreement is what makes the economic terms binding – if the PPM says the preferred return is 8%, that number only has teeth because the governing agreement says so too. The subscription documents are what actually admit the investor into the entity and lock in their representations and warranties – their accreditation status, their acknowledgment that they received and reviewed the risk factors, their agreement to be bound by the Operating Agreement’s terms.
Get all of it right and the package works as a system. The PPM tells the investor the truth. The Operating Agreement makes the deal binding. The subscription documents prove the investor came in with eyes open. That is what actually protects a sponsor – not any single document, but all of them saying the same thing at the same time.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.