The Difference Between Buying a Document and Structuring a Deal
When you hire a syndication attorney, you are not buying a standalone Private Placement Memorandum. You are hiring someone to structure a cohesive legal package that matches how your deal actually operates.
That distinction sounds subtle. It is not. A PPM is one document in a set that has to work together, and the document itself does not fix a deal that is built wrong underneath it.
The sponsor’s real job here is not to acquire a form. It is to build a structure the sponsor and the investors can live with after the money comes in.
The Commodity Document Trap
A lot of sponsors treat legal work as a cheap checkbox on the way to raising money. Fill out the form, get the PDF, start the raise. That is the trap.
The flat-fee “form-filler” websites feed that instinct. They sell a copy-paste template that looks like a finished document. What you get back is a generic file with your name dropped into the blanks.
The problem is that a template does not know anything about your deal. It does not know how you are getting paid. It does not know whether your manager authority is broad enough to handle the changes that always come up once you are operating.
A structural advisor asks those questions before drafting a word. Is the compensation structure sound, or does it create a broker-dealer registration problem? Is the manager authority drafted broadly enough that you are not stuck the first time you need to refinance or replace a service provider?
A template cannot make those calls. It just documents whatever assumptions the template author baked in, and those assumptions are almost never your deal.
The Cohesive Legal Package
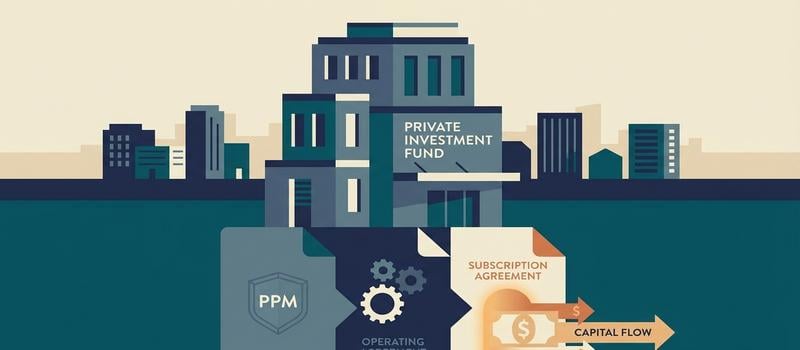
A real syndication legal package is a set of documents that have to talk to each other. The core pieces are the Operating Agreement (or the Limited Partnership Agreement, if you are using an LP), the Subscription Agreement, the Investor Questionnaire, and the PPM.
Each one does a specific job. The Operating Agreement or LPA defines who runs the issuer and how the economics work. The Subscription Agreement controls how an investor actually gets in. The Investor Questionnaire captures accreditation and suitability facts. The PPM explains and discloses the offering.
The trouble starts when these documents do not agree. If the waterfall in the PPM says one thing and the Operating Agreement says another, you now have two versions of how investors get paid.
That is not a typo you fix later. That is an operational and legal problem. Your administrator will not know which document to follow, and an unhappy investor’s lawyer will read the version that helps their client.
When the documents come from one attorney who structured them as a set, they line up. When they come from four templates stitched together, they usually do not.
Why Asking “Can You Draft My PPM?” Is the Wrong First Question
When a sponsor calls and the first question is “Can you draft my PPM?”, they are already thinking about the wrong thing. The PPM is one piece of the disclosure record, not the deal itself. Structuring the offering properly is what actually protects you, and that is a much bigger job than typing a document.
The Actual Legal Requirement for a PPM
Here is the technical rule. Under Rule 506(b), if every investor in your offering is accredited, the SEC does not strictly require you to hand out a formal Private Placement Memorandum. Regulation D has specific mandatory disclosure obligations that kick in when non-accredited investors are involved, and with an all-accredited raise, those specific line items fall away.
So on paper, you could run an all-accredited 506(b) deal without a PPM.
The practical answer is that you almost always want one anyway. The federal anti-fraud rules do not disappear just because your investors are accredited. You are still on the hook for what you said and, just as importantly, for what you failed to say.
A PPM is the central piece of your disclosure record. It is where you lay out the risks, the conflicts, the fees, the structure, and the things that could go wrong. If an investor later claims you left out something material, the PPM is your evidence that you disclosed it.
So the question is not really “Is a PPM required?” The question is “Do I want a documented record showing I told investors the truth?” The answer to that is yes, essentially every time.
The Document Does Not Fix a Bad Structure
A perfectly drafted PPM cannot save a deal that does not work. The document describes the structure. It does not repair it.
If the underlying economics are broken, a clean PPM just gives you a clean description of a broken plan.
Take the waterfall. Say the sponsor wants an 8% preferred return, then a return of capital, then a tiered promote that changes at a 15% IRR, and again at a 20% IRR, with a catch-up in the middle and a clawback at the end. That can be written down. The real question is whether anyone can actually calculate it each quarter and each time you sell an asset.
If the answer is no, the PPM has now documented a distribution scheme you cannot administer. You have not solved anything. You have created a promise you will struggle to keep, and every distribution becomes an argument.
This is why the drafting is downstream of the structuring. The attorney’s job is to look at how you plan to raise, fund, and operate the deal, and make sure the economics hold together before anyone writes them into a PPM.
Evaluate the lawyer on that. Not on how fast they can produce the document.
Why Real-World Syndication Experience Actually Matters
A general securities attorney knows the rules. A syndication specialist knows how the deal actually gets sold, funded, and operated after the rules are satisfied.
That gap matters more than most sponsors expect. You can hire someone who passed the bar, understands Regulation D, and can recite the requirements of Rule 506(b) and Rule 506(c) — and still end up with documents that quietly work against you when you try to raise the money.
The rules tell you what is legal. Experience tells you what is smart.
Separating Legal Theory from Operational Reality
The rule often allows more than you should actually do. The job of an experienced syndication attorney is to know the difference.
Take capital calls. You are legally allowed to draft harsh, punitive capital call terms — dilution, forfeiture, loss of voting rights, the works. A generalist may see that the rule permits it and draft it aggressively because, on paper, it protects the Manager.
Here is the problem. Those terms scare investors. When an investor reads a capital call provision that can wipe out their position, that is a sales problem. Capital walks.
So the real question is not “can we do this?” It is “will this cost us the raise?” You want enough protection that the deal can survive a shortfall, without terms so punitive that the money never comes in the first place.
An experienced attorney draws that line for you. They preserve the Manager’s flexibility to handle a real capital shortage while keeping the terms investors will actually sign.
That balance is not in the statute. It comes from having seen how investors react to specific language across a lot of deals.
The Danger of the Generalist
The most common generalist mistake is treating a syndication LLC like a tech startup.
A corporate attorney who spends their days papering venture rounds reaches for the tools they know. They draft the Operating Agreement around equity classes, option pools, board control, vesting, and a straight pro-rata split on exit. That structure works fine for an operating company chasing growth.
It does not work for a passive investment vehicle. A syndication is not built to grow and get acquired. It is built to hold assets, generate cash flow, and distribute money to investors according to a specific economic deal.
The generalist version usually misses the parts that make a syndication a syndication. There is no proper distribution waterfall. The preferred return mechanics are vague or absent. The treatment of a capital event — a refinance or a sale — does not match what the sponsor pitched to investors.
Here is why that is dangerous. The Operating Agreement is the contract that controls who gets paid, in what order, and how much. If it does not encode the actual economics — the preferred return, the split above the pref, the return of capital on a sale — you have a document that contradicts your own pitch.
Now the PPM says one thing and the Operating Agreement says another. That is not a typo you fix later. That is a structural conflict between the documents that govern real money, and it is exactly the kind of gap that fuels an investor dispute when a distribution does not land the way someone expected.
A syndication attorney builds the waterfall first, then makes every document reflect it. That is the difference between someone who knows the rules and someone who knows the deals.
The Hidden Regulatory Risks a Template Cannot Catch
The real danger with a commodity template is not the sloppy language you can see. It is the deal-specific fact the template never asked about. Two of those facts show up over and over: how the sponsor gets paid, and how the deal gets marketed.
Both are places where a form-filler stays silent and an experienced attorney starts asking questions.
The Broker-Dealer Trap
Sponsor compensation is where a lot of first-time offerings quietly go sideways. A template just fills in a management fee and an acquisition fee and moves on. It does not stop to ask how you are actually getting paid, or whether any part of that pay is tied to the money you raise.
That distinction matters. If your compensation is structured so that you look like you are being paid a commission for selling securities, that can create serious broker-dealer registration risk.
I am being precise on purpose. This is not an “automatic violation.” It is a fact-specific analysis that depends on how the fees are described, what triggers them, and what you are actually doing to earn them.
An inexperienced attorney — or a template with no attorney behind it — often structures a capital-raising fee without ever flagging the issue. The document reads fine. The problem is buried in the economics, and nobody who could catch it ever looked.
The practical answer is that your compensation structure has to be reviewed against how the deal actually works, not just typed into a fee schedule. That review is the whole point of hiring someone who does this for a living.
Solicitation and Marketing Alignment
The second fact a template ignores is how you plan to find investors. That is not a document question. It is a structural question, and it changes which exemption you are relying on.
Under Rule 506(b), you cannot generally solicit. That affects what you can put on your website, what you can post, and how you talk about the deal in public. Under Rule 506(c), you can advertise, but every purchaser has to be accredited and you have to take reasonable steps to verify it.
A template does not know which path you are on. It certainly does not review your website, your pitch deck, or your email list against that path.
This is where the attorney’s job runs past drafting. Part of what you are paying for is help addressing these marketing questions before you make a filing decision you cannot walk back.
Be clear on what a lawyer can and cannot do here. No attorney can “ensure compliance,” because compliance depends on what you actually do — what you post, who you talk to, how you verify accreditation. The lawyer helps structure the offering and supports the legal package. You still have to operate it correctly.
That division of labor is exactly why the structure has to be right on the front end. Once the money starts coming in, your room to fix a marketing or compensation problem gets a lot smaller.
The ‘Plain-English’ Litmus Test for Hiring Counsel
Here is the simplest way to evaluate a securities attorney: if they cannot explain the rules and your deal structure in plain language, they will become a bottleneck for both your operations and your investor relations.
The documents you sign are the documents you have to explain. Your investors will ask you why the waterfall works the way it does, what the manager can and cannot do, and what happens if a capital call comes. If your own attorney could not make those things clear to you, you will not be able to make them clear to your investors.
Evaluating Communication During the Interview
Ask a technical question during the interview and watch how the attorney answers it. Ask something like, “What happens if I want to bring in a new investor after the first closing?” or “How does a 506(b) offering differ from a 506(c) offering for my website?”
If the answer comes back in deep legalese — statute citations, defined terms, and qualifications stacked on qualifications — that is a failing grade. Not because the citations are wrong, but because you now know how every future conversation will go.
The practical answer to “what happens if I bring in a new investor later” is short. You review whether they qualify, you make sure the offering is still open, they sign the subscription documents, and you update the books. If the attorney cannot get there without a fog of terminology, that fog will follow you into every investor call.
You are not hiring a translator you have to translate. You are hiring someone who makes you smarter about your own deal.
Specific Questions to Ask a Prospective Attorney
Ask two concrete questions before you hire anyone.
First: “How much of your practice is strictly Regulation D syndications and funds versus general corporate work?” You want a real number. Someone who does Reg D offerings all day has seen the problems that only show up after the money comes in. Someone who does this occasionally, between commercial contracts and business formations, has not.
Second: “How do you make sure the Operating Agreement or LPA aligns with my specific financial model and waterfall?” This is where generalists get exposed. If the answer is vague, or if they treat the operating agreement as a standard form they drop your names into, the economics in your model and the economics in your documents will not match. That mismatch becomes an accounting problem and an investor problem later.
What you are really looking for is a business partner who understands risk mitigation and how the deal actually operates — not a typist generating a commodity document. The document is the easy part. The structure underneath it is the thing you are actually paying for.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.