Do You Actually Need a PPM to Raise Capital?
The technical answer and the practical answer are not the same. Under Regulation D, a Private Placement Memorandum may be required depending on your investor mix and facts – it is strictly mandated only when you accept non-accredited investors. So if you are raising from accredited investors only, the rule does not force you to hand out a specific disclosure document.
The practical answer is different. Even when a PPM is not strictly required, it is usually the center of your disclosure record. Raising money from anyone without a comprehensive disclosure document leaves you exposed to anti-fraud liability, and that exposure does not care whether your investors were accredited.
If you want the baseline explanation of what this document is and does, see what a PPM is. This section is about whether you can skip it.
The Technical Rule vs. The Practical Reality
Rule 502(b) does not demand a specific disclosure document when you sell only to accredited investors. That part is real. On paper, an accredited-only offering under Rule 506(b) or Rule 506(c) does not trigger the mandatory information requirements that kick in for non-accredited investors.
Here is where sponsors get into trouble. Being exempt from SEC registration is not the same as being exempt from providing paperwork. Those are two different questions, and people collapse them into one.
The dangerous assumption sounds like this: “I don’t have to register, so I don’t need a PPM.” That skips over the anti-fraud rules entirely, and the anti-fraud rules are where the real risk lives.
Saving a few thousand dollars on drafting upfront can create an existential problem on the back end. If the deal loses money and an investor sues, you want a written record of what you told them. Without a PPM, you are defending that lawsuit with a pitch deck and your memory of a phone call.
The Hidden Liability Sponsors Miss
The PPM is not a form you file with the SEC. It is not a regulatory checkbox. Its real job is to protect you.
Think of it as your record of disclosure. It is the document that proves what the investor was told – the risks, the fees, the conflicts – before they wrote the check.
That is the point most sponsors miss. The PPM is written less for the investor and more for the day an investor’s lawyer argues you hid something. When you have a comprehensive PPM, you can point to the page where the risk is disclosed. When you don’t, you are arguing about what was said in a room with no witnesses.
That is why I treat the PPM as central to the disclosure record on almost every deal, even when the rule technically leaves it optional.
The Difference Between Reg D Exemptions and Anti-Fraud Rules
Regulation D can exempt you from filing formal disclosure paperwork for certain investors. It does not exempt you from Rule 10b-5, which makes it illegal to lie to an investor or hide a material fact from anyone. The PPM is how you prove you didn’t.
The mistake sponsors make is treating these as the same body of law. They are not. Reg D is your ticket out of SEC registration. Rule 10b-5 is the anti-fraud rule that follows you around no matter which exemption you claim.
What Rule 502(b) Actually Says
Rule 502(b) is the disclosure section of Regulation D, and it is narrower than most people assume.
The rule triggers specific information requirements when an issuer sells to non-accredited investors. That is when you are forced to hand over defined categories of information – business history, financial statements, and in larger offerings, audited financials.
For an offering restricted solely to accredited investors, Rule 502(b) is essentially silent. It does not prescribe a mandatory disclosure document or a required delivery format.
So on a plain reading of Rule 502(b) alone, an accredited-only issuer is not compelled to produce a PPM. That is the technical answer, and it is where a lot of sponsors stop reading. The problem is that Rule 502(b) is not the only rule in the building.
Why Rule 10b-5 Overrides the Technicalities
Rule 10b-5 is the anti-fraud rule, and in plain English it says two things. You cannot make an untrue statement of a material fact. And you cannot leave out a material fact that would change how an investor sees the deal.
There is no accredited exemption from Rule 10b-5. It applies to your wealthiest investor and your least sophisticated one, in a 506(b) deal, a 506(c) deal, or a registered offering. A material fact is anything a reasonable investor would want to know before writing the check – a fee you are taking, a conflict you have, a risk that could sink the deal.
Now think about the evidence problem. If your only record is a pitch deck and a few conversations, you have almost nothing showing what risks you actually disclosed.
When a deal loses money, that gap becomes a fight. The investor says, “You never told me about that risk.” You say, “Yes I did, on a call.” There is no document, so it comes down to whose memory the court believes. That is a fight you do not want, and it is one you can avoid.
How the PPM Solves the Anti-Fraud Problem
Its function is to serve as the written record of what you told the investor before they invested.
A well-drafted PPM lays out every material risk, every conflict of interest, and every fee. It puts the hard facts in front of the investor in writing – not the optimistic version from the pitch deck, the full version.
That written record is what helps address a Rule 10b-5 claim. An investor cannot credibly say they were kept in the dark about a risk that is spelled out in a document they received and signed for. The disclosure is on paper, with a date, and the investor acknowledged it.
None of this guarantees you never get sued. What it does is move you from a he-said, she-said fight to a documented record that shows what the investor was told. That is why sophisticated sponsors treat the PPM as central to the disclosure record even when Rule 502(b) does not strictly require one.
When the SEC Strictly Mandates a PPM (Rule 506(b))
Rule 506(b) is where the disclosure requirement stops being a choice.
The moment a sponsor accepts even one non-accredited investor under Rule 506(b), Rule 502(b) forces the issuer to deliver comprehensive disclosures. At that point, the required disclosure package looks a lot like what you would see in a registered public offering.
The Burden of Non-Accredited Disclosures
The SEC treats non-accredited investors as people who need protecting. The assumption is that they cannot absorb a total loss and cannot easily fend for themselves, so the rule shifts the burden onto the issuer to tell them everything.
In practice, that means the issuer has to provide extensive business and financial information. Depending on the size of the offering, that can include multi-year business history, financial statements, and in larger deals, audited financials.
This is expensive. Audited financials alone can cost real money and take real time, especially for a new operating company or fund that does not have clean historical books.
That is exactly why most sponsors just exclude non-accredited investors entirely. It is not that they dislike those investors – it is that letting one in triggers a statutory disclosure burden they would rather avoid.
Here is the distinction that matters. For an accredited-only offering, drafting a PPM is a voluntary risk-management choice you make to protect yourself under the anti-fraud rules. For a deal with non-accredited investors, the disclosure obligation is a forced statutory requirement, and a PPM is the normal way issuers satisfy it.
Same document, two very different reasons for producing it.
The Sophistication Requirement
Non-accredited investors under Rule 506(b) come with a second hurdle. They must also be “sophisticated,” meaning they – alone or with a purchaser representative – are capable of evaluating the merits and risks of the investment.
Being sophisticated is not the same as being accredited. Accredited is about money. Sophisticated is about the ability to actually understand what you are buying.
Here is the practical problem. If the investor has to be capable of evaluating the merits and risks, you have to actually give them the merits and risks to evaluate. You cannot claim someone made a sophisticated decision if you never handed them the information a sophisticated person would need.
That is what the PPM does. It lays out the business, the risk factors, the fee structure, and the conflicts in one place, so the non-accredited investor has a real basis to make the evaluation the rule assumes they made.
Without it, you are asserting the investor was sophisticated while giving them nothing to be sophisticated about.
The Retroactive Reclassification Trap: Why ‘Accredited-Only’ Can Backfire
Here is the danger most sponsors never see coming. You run an “accredited-only” 506(b) offering, skip the PPM to save money, and everything is fine until the deal loses money. Then an investor’s accredited status gets challenged, and you are suddenly judged under the strict disclosure rules you thought did not apply to you.
The assumption that “everyone was accredited” is not a fact. It is a bet. And if you lose that bet in litigation, the missing PPM becomes the thing that sinks you.
How Investors Lose Their Accredited Status
Under Rule 506(b), most sponsors verify accreditation through self-certification. The investor fills out an Investor Questionnaire, checks the box that says they meet the income or net-worth test, and signs it. You take their word for it, which the rule allows.
That works fine until the deal goes bad.
When an investor loses money, a plaintiff’s attorney does not start with your disclosures. They start with the investor’s status. They pull tax returns, bank statements, and net-worth calculations from the time of the investment, looking for any way to prove the investor was not actually accredited when they wrote the check.
People overstate their finances. Someone counts home equity they were not allowed to count, or reports household income that was really one spouse’s income two years ago. The questionnaire said “accredited.” The reality, under a hostile audit, might say something else.
The Catastrophic Consequence of Missing Disclosures
If a court reclassifies that investor as non-accredited, your offering gets re-judged under Rule 502(b). Now you are held to the full disclosure requirements that apply when a non-accredited investor is in the deal – the extensive business history, the financial statements, all of it.
You skipped the PPM because you did not think you needed it. That decision now reads as a direct failure to provide mandatory disclosures.
The consequence is not a fine. It is potentially a blown exemption. When the exemption fails, the securities were sold in violation of registration requirements, and that can trigger rescission rights. Rescission means the investor gets to unwind the deal and force you to return their capital – often with interest – regardless of what happened to the underlying assets.
That is the trap. The one investor you never bothered to verify becomes the reason every dollar has to go back.
The PPM as Your Fallback Insurance
A voluntary PPM changes the math on all of this. If you provided a comprehensive disclosure document to every investor, accredited or not, the reclassification stops being fatal.
You can point to the PPM and show the court that this investor received the material risks, the conflicts, the fees, and the business background – the same disclosures Rule 502(b) would have demanded anyway. The reclassification still matters, but the disclosure gap that usually triggers rescission is gone.
This is why treating the PPM as optional under “accredited-only” logic is a mistake. The PPM is not just how you satisfy disclosure when the rule requires it. It is how you protect yourself when someone later argues the rule required it all along.
You cannot control whether an investor lied on a questionnaire. You can control whether you handed them a real disclosure document. If it were me, I would build the PPM every time and take that whole line of attack off the table.
Rule 506(c) and the Myth of the ‘No-Paperwork’ Offering
Some sponsors assume Rule 506(c) simplifies everything. Every investor is verified as accredited, so the strict disclosure rules for non-accredited investors never apply. From there, the logic goes: no non-accredited investors means no mandatory disclosures, which means no PPM.
That logic is backwards. Under 506(c), your need for a tightly controlled PPM goes up, not down.
The reason is what 506(c) lets you do. It lets you advertise. And the moment you advertise, you multiply the number of people who can claim you misled them.
General Solicitation Amplifies Risk
Rule 506(c) permits general solicitation. You can put the deal on your website, talk about it on a podcast, run ads, and email people you have never met.
That is a real advantage for raising money. It is also a much wider funnel for liability.
More eyes means more people reading your marketing. It means more regulators potentially watching. And it means more chances that someone points to a single bullet point on a pitch deck and says they invested because of it.
Anti-fraud liability under Rule 10b-5 does not soften because your investors are verified accredited. Wealthy investors sue too. A verified accredited investor who loses money can still argue you overstated the upside or buried the risk, and now that argument is attached to marketing material you broadcast to the public.
Anchoring Your Marketing to the PPM
Your pitch deck and website cannot stand on their own. They need to sit underneath the PPM.
The problem with marketing material is that it is short and optimistic by design. A pitch deck shows the projected return and the best-case story. It does not have room for the full risk factors, the fee structure, the conflicts of interest, and the honest downside.
The PPM does. That is its job. It is the document that gives the investor the complete picture behind the marketing.
So the practical rule is simple: every claim you make in your marketing should trace back to something disclosed in the PPM. If the deck says “targeting 15%,” the PPM explains the assumptions, the risks, and the fact that projections are not guarantees.
When you deliver the PPM and the investor acknowledges receiving it, you change the story an investor can later tell. They cannot credibly claim they only saw the optimistic slide when the full disclosure document was in their hands before they wrote the check.
That does not make the deal bulletproof. But it means your marketing is anchored to a real disclosure record instead of floating on its own, which is exactly the exposure you do not want when you have been soliciting the general public.
Why a Standalone PPM Is Useless Without the Full Legal Package
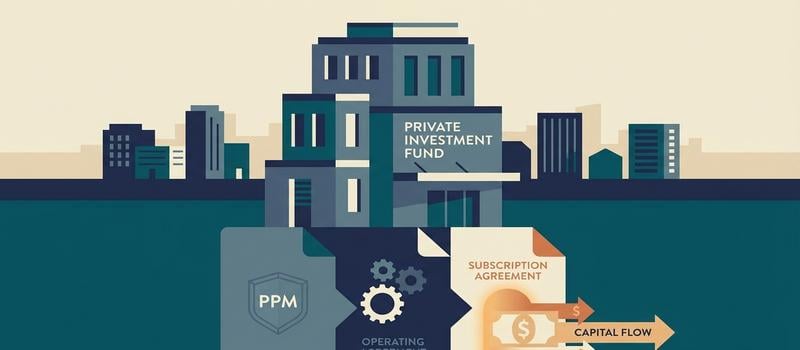
No, a sponsor cannot just buy a PPM template and call it a day. A PPM explains the offering, but it has no power to govern the company or bind the investor. It only works when it is structurally tied to the Operating Agreement and the Subscription Agreement.
Disclosure vs. Governance
The PPM tells the story. It tells the investor what the deal is, what the risks are, how the money moves, and what the sponsor gets paid. That is disclosure, and disclosure is how you address the anti-fraud rules.
But disclosure does not run the company.
The Operating Agreement (or the Limited Partnership Agreement, if you are using an LP) is the actual contract. It is what gives the sponsor the legal authority to make capital calls, decide distributions, sign on behalf of the entity, and manage the assets.
Think of it this way. The PPM describes the powers. The Operating Agreement grants them. If the PPM says the manager can call capital but the Operating Agreement is silent or says something different, the PPM does not save you. The governing document controls.
Locking the Investor In
The Subscription Agreement is the bridge between the disclosure and the governance. It is where the investor actually commits.
When an investor signs the subscription documents, they represent that they received and read the PPM, that they understand and accept the risks, and that they agree to be bound by the Operating Agreement. The Investor Questionnaire sits alongside it to establish accreditation and, under 506(b), sophistication.
That is what turns a disclosure document into a defensible record. The investor is not just told the risks – they sign a document acknowledging they were told.
So the full-package point is simple. A well-drafted PPM helps structure the offering and helps address the anti-fraud rules, but it only functions as part of a unified set: PPM, Operating Agreement, Subscription Agreement, and Investor Questionnaire, all drafted to work together. That is what a real private placement memorandum legal package actually is – not a standalone document, but a set of agreements built to work as one.
Where sponsors get hurt is mixing sources. A PPM from one place and an off-the-shelf Operating Agreement from another almost always conflict – different fee language, different manager rights, different distribution waterfalls. Now you have two documents saying two things, and a plaintiff’s lawyer gets to pick which one to use against you.
If it were me, I would not buy a standalone PPM. I would build the package so the documents agree with each other. For the difference between disclosing the deal and legally governing the entity, see our discussion of the Operating Agreement in a Reg D offering.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.