The Mindset Shift: You Are No Longer Just Buying Real Estate
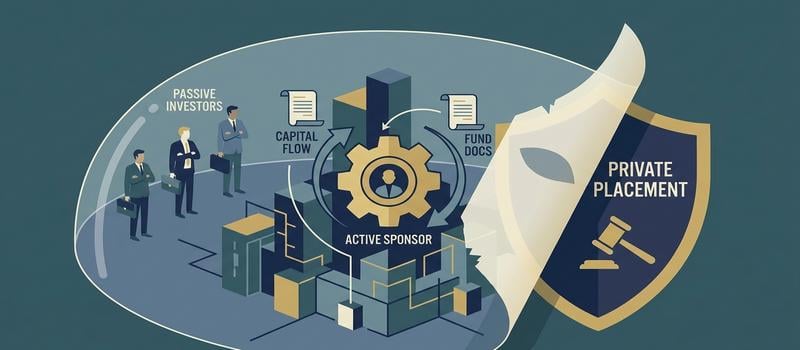
When you syndicate a multifamily property, you are not just buying real estate anymore. You are issuing a private security. That single fact puts you under the Securities and Exchange Commission’s rules, and it changes how you raise money, what you disclose, and what you can promise.
A lot of new sponsors miss this. They think that because the asset is an apartment building, the deal is a real estate deal and nothing more. It is not. The moment you take money from passive investors, you have created a real estate syndication, and that offering is a security you have to sell under an exemption.
The practical consequence is simple. You cannot just pool your friends’ money into an LLC and hope it works out. You need a framework, and for most sponsors that framework is Regulation D.
The Howey Test Reality
The test for whether you have a security is the Howey test, and it is easier to trigger than most sponsors expect.
You have a security whenever you pool money from passive investors who expect a return generated primarily by your efforts. That is it. If your investors are writing checks and waiting for you to find the deal, close it, and run it, you have created a security.
The SEC does not care that the underlying asset is bricks and mortar. The building is not the security. The interest you sell in the entity that owns the building is the security. So even though it feels like a real estate transaction to you, the offering is treated as an investment contract, and it is regulated like one.
The Practical Difference Between a Joint Venture and a Syndication
A true joint venture and a syndication are not the same thing, even though sponsors use the words loosely.
In a real joint venture, everyone is active. All the partners have control and real decision-making power. Nobody is sitting on the sidelines waiting for someone else to make the money. When everyone is genuinely running the deal together, you are usually not in securities territory.
A syndication works differently. Your limited partners trade control for limited liability. They do not manage anything. They rely entirely on you, the sponsor, to make the decisions and generate the return.
That separation of capital and control is exactly what turns the deal into a security. The people putting up the money are not the people running the business. That is the gap Regulation D exists to fill, and it is why you need an exemption instead of a handshake.
The Two-Entity Baseline: Separating Management from the Asset
Once you accept that you are issuing a security, the next question is how to hold it. The answer for almost every multifamily syndication is a minimum of two entities: a Manager LLC that runs the deal, and an Investment LLC that owns the property and issues the interests.
The point of splitting them is simple. You want your active management activity in one entity and the investor capital and the real estate in another, so a problem in one does not reach into the other or into your personal assets.
Why a Single LLC Fails
Running everything through one LLC is the most common mistake I see, and it defeats the purpose of forming an entity at all.
Here is the problem. If the property, the investor capital, and your management activities all sit in the same LLC, then every operational risk from that property lives in the same box as everything else. A slip-and-fall in the parking lot, a tenant dispute, a construction claim – all of it now sits alongside the money you raised.
That also creates friction you do not need. You are mixing your active management role with the passive capital of your investors in one set of books, which muddies the accounting, the tax reporting, and the lines of authority. Investors do not want their capital co-mingled with your operating business, and frankly, you do not want it either.
The Manager LLC (The GP Tier)
The Manager LLC is the entity you and your active partners own. It is the general partner tier of the structure.
This entity does not hold the real estate. It does not hold investor money. It exists to make decisions, sign contracts, and collect the compensation you earn for running the deal – management fees and your promote.
The reason to isolate this entity is control and risk. Your active management decisions carry their own liability exposure, and you want that exposure sitting in an entity that does not also hold the asset or the capital. If someone comes after the manager, they are not reaching the property, and they are not reaching the investors.
The Investment LLC (The Issuer Tier)
The Investment LLC is the entity that actually issues the securities. It holds the investor capital, it takes title to the multifamily property, and it is the “issuer” the SEC cares about under Regulation D.
Investors buy their interests in this entity. Their money goes in here, the property is owned here, and their economic rights are defined here.
The Manager LLC is then appointed to manage the Investment LLC. That appointment is what ties the two tiers together and gives you a clean structure: the sponsor controls the manager, the manager runs the issuer, and the issuer owns the asset. That is the two-tiered shield professional syndications are built on.
The SEC Rulebook: Choosing Between Rule 506(b) and 506(c)
Once your entity stack is in place, the next decision is which Regulation D exemption you raise under. Almost every multifamily syndication runs on Rule 506(b) or Rule 506(c).
The choice comes down to two things: whether you can publicly advertise the deal, and how carefully you have to check who is writing you a check. Pick the wrong one and you can blow the exemption, which is the worst outcome in this whole exercise.
The Rule 506(b) Path: Relationships Over Advertising
Rule 506(b) is the private path. You cannot generally solicit, which means no public advertising of the offering – no website landing pages pitching the deal, no social media posts, no podcast plugs, no cold outreach to strangers.
The rule requires a substantive, pre-existing relationship with each investor before you show them the deal. In plain English, you have to actually know the person – their finances, their situation, their sophistication – before the offering comes up. You cannot meet someone on Tuesday and pitch them the deal on Wednesday and call it a relationship.
Now the part that gets sponsors in trouble. 506(b) technically lets you take up to 35 non-accredited investors, and a lot of blogs treat that like a feature.
It is not a feature. It is a trap.
Those non-accredited investors still have to be sophisticated, meaning they have the knowledge and experience to evaluate the deal on their own or through a purchaser representative. That is a judgment call you have to defend later if things go sideways.
More important, the moment you accept even one non-accredited investor, your disclosure burden explodes. You now owe them a much heavier set of financial disclosures – audited financials in many cases – plus a full narrative disclosure of the deal.
That is real money and real time, and it raises your regulatory exposure for no good reason. In the real world, most professional sponsors run 506(b) as an all-accredited offering. They keep the relationship requirement and skip the non-accredited headache entirely.
The Rule 506(c) Path: Public Solicitation and Strict Verification
Rule 506(c) flips the advertising rule. You can generally solicit – website, podcasts, LinkedIn, webinars, whatever you want. You can put the deal in front of the public and let people come to you.
That freedom comes with a hard tradeoff. Every single purchaser must be accredited. There is no 35-investor cushion, no sophisticated-but-non-accredited exception. If one non-accredited investor gets in, the exemption is gone.
And you cannot just take their word for it. Under 506(c), you have to take reasonable steps to verify accredited status – you are not allowed to rely on a checkbox where the investor swears they qualify.
Verification usually means reviewing tax returns, W-2s, or brokerage statements, or getting a letter from the investor’s CPA, attorney, or registered advisor confirming they are accredited. Most sponsors use a third-party verification service so they are not personally sitting on someone’s tax returns.
The practical way to think about it: 506(b) buys you the ability to take a few non-accredited friends and family, at the cost of silence. 506(c) buys you the ability to advertise, at the cost of verifying everyone. If you plan to market the deal at all, use 506(c) and verify. If you are raising quietly from people you already know, 506(b) is usually cleaner.
The Legal Trifecta: The Documents That Govern the Deal
Three documents do the real work in a syndication: the Private Placement Memorandum, the Operating Agreement, and the Subscription Agreement. Each has a distinct job. The PPM handles disclosure, the Operating Agreement handles the rules, and the Subscription Agreement handles execution.
Get all three right and they reinforce each other. Get one wrong and the other two cannot cover for it.
The Private Placement Memorandum (PPM)
The PPM is the disclosure document. Its job is to tell the investor everything that could go wrong with the deal before they wire a dollar.
That includes the obvious things and the uncomfortable things: leverage risk, vacancy risk, interest rate risk, sponsor conflicts, illiquidity, the possibility that the whole business plan does not work and the investor loses their money.
Sponsors often treat the PPM as a marketing piece. It is not. It is defense.
If the deal underperforms and an investor claims you misled them, the PPM is your primary protection against an anti-fraud claim. The rule under Rule 10b-5 is that you cannot make a material misstatement or leave out a material fact. A PPM that clearly disclosed the risk that actually occurred is how you show you did not hide anything.
That is why the PPM has to be specific to your deal. A generic template that lists boilerplate risks does not describe your asset, your market, your debt structure, or your business plan. When it does not match the deal, it does not protect you.
Retaining legal services for real estate syndication sponsors is largely about making sure this document actually maps the specific risks of your asset class and your plan, not somebody else’s.
The Operating Agreement
The Operating Agreement is the rulebook for the Investment LLC. Where the PPM discloses, the Operating Agreement governs.
It controls the mechanics that matter after the money comes in: the waterfall that decides who gets paid and in what order, the sponsor’s compensation, voting rights, and the conditions under which the manager can be removed.
This is the document that decides whether you can actually run the deal.
If you draft it so every material decision requires an investor vote, you have handed control back to the people who signed up to be passive. Now you cannot refinance, sign a new management contract, or handle a problem without holding a vote.
Preserve manager discretion. The Operating Agreement should let you operate the property, make normal business decisions, and respond to problems without constantly asking limited partners for permission. Reserve the big-ticket votes – selling the asset, admitting new members, amending the agreement – and keep the rest in the manager’s hands.
Do not put yourself in a box to make the deal look investor-friendly. A deal you cannot operate is worse for everyone.
The Subscription Agreement
The Subscription Agreement is the contract the investor signs to buy units in the Investment LLC. This is how they actually get in.
It does two things. It documents the purchase – how many units, at what price, on what terms. And it collects the representations you need from the investor.
Attached to it is the investor questionnaire. That questionnaire establishes whether the investor is accredited, and under Rule 506(c) it is the starting point for verifying that status. It also confirms the investor received and read the PPM.
That last point matters. If an investor later claims they never saw the risk disclosures, the signed subscription documents are your record that they did.
Compensation Traps: Broker-Dealer Risks and “Guaranteed” Returns
How you pay yourself is where a lot of sponsors quietly break the law. Two mistakes show up constantly: charging a fee for raising the money, and telling investors their return is guaranteed. Both create problems you do not need.
The rule is simple to state. You can be compensated for managing the deal and for the equity you earn as a promote. You cannot be paid a commission for selling securities unless you are a licensed broker-dealer.
The Danger of “Equity Raise Fees”
Charging an “equity raise fee” – a percentage of the capital you bring in – is transaction-based compensation, and that is exactly what triggers broker-dealer registration.
A lot of generic industry blogs treat this as normal. They describe a sponsor or a capital partner taking, say, 2% of everything they raise, as if that were just a line item in the budget.
It is not just a line item. Section 15(a) of the Exchange Act says you have to be registered as a broker-dealer to be in the business of effecting securities transactions. Paying someone based on how much capital they raise is the textbook definition of what a broker does.
The problem is not only the fine. If you paid an unregistered person a transaction-based fee, investors may have a rescission right – meaning they can demand their money back. That is a mess you carry for the life of the deal.
So how do you get paid for the work of putting the deal together? You structure it under the Issuer Exemption, Rule 3a4-1, which lets certain associated persons of the issuer participate without registering, as long as they are not paid based on the size of the raise.
In practice, that means your compensation comes from acquisition fees, asset management fees, and your equity promote – not a commission tied to dollars raised. The promote rewards you for performance over the life of the deal. That is fine, and it keeps you on the right side of the line.
The Reality of Preferred Returns
There is no such thing as a guaranteed return in an equity syndication. Using words like “safe,” “guaranteed,” or “risk-free” in your marketing violates SEC anti-fraud provisions, full stop.
A preferred return is not a guarantee. It is a priority.
In plain English, a preferred return means the limited partners get paid first, up to their preferred rate, before you as the sponsor take any promote. Say the investors have an 8% pref. If the property produces cash, the first dollars go to them until they hit 8%.
But if the property does not produce cash, nobody gets paid – including them. The pref sets the order of the waterfall. It does not manufacture money that the deal did not earn.
Describe it accurately in your PPM and your marketing. Tell investors the pref is a distribution priority, not a promise. When the deal performs, they see it. When it does not, the pref simply accrues or sits unpaid, depending on how you drafted it.
The clean version is honest and still attractive: “Investors receive an 8% preferred return, meaning they are paid before the sponsor earns a promote.” That is true, it protects you, and it is the version I would put on paper.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.