The Short Answer: What a Convertible Promissory Note Actually Is
A convertible promissory note is a loan that can turn into equity. The sponsor borrows money from an investor now, and under the terms of the note, that debt can later convert into a membership interest in the syndication’s LLC instead of getting paid back in cash.
That dual nature is the whole point. It starts as debt, but it carries an option to become an ownership position in the deal.
And because it carries that option, it is a security. That matters more than most sponsors expect, so it is worth being precise about how the instrument actually works.
The Hybrid Nature of the Instrument
The note works as a bridge. It gives the sponsor immediate capital to move on a deal, and it gives the investor a priority claim on repayment ahead of the equity holders while the note is still outstanding.
In plain English, on day one the investor is a lender, not a partner. They have a debt claim, a stated interest rate, and a maturity date.
The conversion is what makes it different from a plain loan. Under conditions written into the note, the outstanding balance stops being a debt and becomes LLC membership interests. At that moment, the investor moves from lender to owner and joins the cap table.
Here is the part sponsors miss. Because the note contains an option to convert into equity, federal and state regulators treat it as a security from the day you issue it, not from the day it converts.
That is not a technicality you can defer. The SEC looks at the option itself as an investment contract, so the note lives under the securities laws from the start.
Treating it as “just a loan” and skipping the securities analysis is where the real exposure comes from. It does not make the note automatically defective, but it leaves the offering open to serious regulatory risk that a properly structured note would have addressed up front.
The Practical Misconception: Why This Is Not a Standard Loan or a Startup SAFE
The most common mistake sponsors make is treating a convertible note like a standard real estate loan or like a tech-startup SAFE. Neither template fits. Syndication economics and securities laws demand a different structure, and copying the wrong document creates problems you do not need.
The ‘Standard Loan’ Trap
A standard promissory note is simple. There is a fixed interest rate, a maturity date, and a payoff. When the borrower pays it off, the relationship ends. Nobody joins anything.
A convertible note is not that. It carries an equity mechanic. The investor is not just a lender who gets paid and walks away – they are a future member of the LLC whose rights have to be anticipated before the money comes in.
That changes what you have to draft. If the note converts, the investor lands on your cap table with economic rights, and possibly voting or information rights, depending on how the note and the Operating Agreement are written. You cannot bolt those rights on after the fact. You have to write them in from the start.
So the practical problem is timing. A standard loan lets you defer the equity conversation forever. A convertible note forces you to decide, in advance, exactly what the investor becomes and what they get when they get there.
Why Tech-Startup SAFEs Do Not Work for Real Estate
A Y-Combinator SAFE is built for a very specific world. It assumes a highly speculative startup with no current valuation, a future priced financing round, and investors betting on a large exit years away. The whole document is designed around an unknown future valuation.
A real estate or fund syndication does not work that way. It is usually yield-driven, and the entity structure – the LLC, the manager, the economic splits – is largely fixed from the start. There is no mysterious future priced round that sets the conversion price.
Drop a startup SAFE into a syndication and the economics break. The conversion terms reference concepts that do not exist in your deal, the valuation triggers point at nothing, and you end up with an unworkable cap table.
If it were me, I would not start from a SAFE at all. The convertible note in a syndication has to be drafted against the actual entity structure and the actual economics of the deal, not a generic startup template that assumes facts your deal does not have.
The Mechanics of the Debt-to-Equity Conversion
The conversion is triggered by specific dates, capital events, or sponsor discretion, and when it fires, the investor’s outstanding debt balance turns into a predefined slice of the LLC equity. That is the whole mechanic. The note stops being a loan and becomes a membership interest in the issuer.
The details matter, because the conversion is where sponsors either preserve their flexibility or create a fight later.
Setting the Conversion Triggers
The trigger has to be hardcoded in the note. You do not want to leave “when we convert” to a handshake or a later conversation.
Common triggers include a maturity date, the closing of a construction loan, or the launch of the main Regulation D offering. Any of those can work. The point is to pick one that matches how the deal actually unfolds.
For example, say the note matures in 18 months, but it also converts automatically when the main 506(b) offering closes, whichever comes first. Now everyone knows the moment the investor joins the cap table.
Keeping that trigger clear is not just tidy drafting. It protects the sponsor’s flexibility and it prevents disputes over when the debt became equity – which is exactly the kind of disagreement that shows up when the money is good and the investor wants in earlier, or when the money is tight and the investor wants to stay a creditor.
If it were me, I would define the trigger tightly and give the manager discretion to convert early where it makes sense. That way you are not boxed in if the timeline shifts.
Navigating GP and LP Terminology
The note usually describes what the investor converts into using “GP” and “LP” language, even though almost every modern syndication is wrapped in an LLC, not a limited partnership.
“General Partner” and “LP” are holdovers. In a real limited partnership, the general partner runs the deal and carries the liability, and the limited partners are passive. Most sponsors do not use that structure anymore. They use an LLC with a manager and members, because the LLC gives the same passive treatment without the personal liability exposure a true general partner takes on.
So in practice, there is no general partner. There is a manager of an LLC.
But the industry still leans on the GP/LP shorthand to describe the economics. When people say the note converts into “LP equity” or a “GP sliver,” they are really describing where the investor lands in the LLC’s economic waterfall – passive investor economics on one side, sponsor-side promote economics on the other.
The drafting has to translate that shorthand into the actual LLC terms. The note and the Operating Agreement need to agree on what the investor becomes: a member holding a specific class of interest, with defined distribution rights, not a “limited partner” in an entity that does not have partners.
If those two documents use different language, you have created ambiguity where you least want it – at the exact point money changes character.
Strategic Use Cases: When to Actually Issue a Convertible Note
Sponsors use convertible notes to solve a timing problem. You need money early, before the deal is ready to show to your main equity investors, and you do not want to lock in final terms yet.
Straight equity forces you to price the deal now. A convertible note lets you take in capital now and settle the equity terms later, when you actually know what the deal looks like.
Bridging the Early-Stage Capital Gap
The convertible note solves the problem of needing capital before the syndication package exists.
In a typical deal, you have costs that hit before you can market to limited partner investors. Earnest money on the purchase contract. Land acquisition. Permitting and entitlement work. Due diligence.
None of that waits for your Private Placement Memorandum to be finished.
A convertible note lets you bring in a smaller group of early investors quickly to cover those costs. You are not building the full offering yet. You are borrowing against it.
The advantage is that you do not have to fix the final valuation or the final LP terms to take the money. The note sits as debt now, and it converts into equity later, once the main Regulation D offering is structured and priced.
That preserves flexibility. If it were me, that is usually the whole reason to use the instrument – you get cash without committing to numbers you cannot yet defend.
Incentivizing Seed Capital with a GP Sliver
Early investors take the most risk, so the conversion terms usually need to reward that risk.
At the seed stage, there is no signed construction loan, no finished PPM, and no certainty the deal closes. An investor writing a check at that point is exposed in a way your later LP investors are not.
To account for that, some sponsors structure the conversion so early money buys into the sponsor side of the deal, not just the investor side. A common approach is a small slice of GP equity – for example, a 1% GP interest for every $100,000 invested.
Whether that specific ratio makes sense depends on your deal economics, your total raise, and how much dilution you can absorb. There is no standard number here.
Understand the tradeoff. Giving away a piece of your GP economics dilutes you permanently. You are trading long-term upside for short-term liquidity.
Most of the time that trade is worth it. A project that never launches because you could not fund the earnest money is worth nothing. A project that launches, with you giving up a few points of GP equity to the people who made it possible, is worth quite a lot.
The point is to be deliberate about it. Decide what the early capital is actually worth to you, and write the conversion terms to match – do not just default to a number you saw someone else use.
The Reg D Compliance Trap: Why You Still Need a PPM
A convertible note is a security, so issuing one pulls you into the same securities framework as a straight equity raise. That means you still need real disclosure, including a Private Placement Memorandum, and you still have to fit inside an exemption under Regulation D.
The mistake I see is sponsors treating the note as if it lives outside the securities world because it starts as debt. It does not.
The “It’s Just Debt” Illusion
The SEC looks at the option to convert into LLC equity and sees an investment contract. The investor is not making a plain loan. They are betting on the upside of the venture, and that expectation of profit from your efforts is exactly what makes it a security.
So an offering built around convertible notes generally carries the same disclosure obligations as a traditional equity syndication. You are not skipping the PPM, the subscription documents, or the risk factors just because the instrument is labeled a note.
You also still have to pick an exemption. Most sponsors are relying on Regulation D, which means Rule 506(b) or Rule 506(c).
Under Rule 506(b), you cannot use general solicitation to find your note investors. No advertising the note, no public posts, no cold outreach to people you do not have a real, preexisting relationship with. The offering has to stay private.
Under Rule 506(c), you can advertise the note publicly, but every purchaser must be accredited, and you have to take reasonable steps to verify that accredited status. A self-checked box on a questionnaire does not meet the 506(c) verification standard.
The point is simple. The exemption you choose controls how you can raise the note money, and that choice does not change just because the security is a note instead of a membership interest.
The Broker-Dealer Trap for Finders
Sponsors sometimes pay an unregistered “finder” a fee to bring in convertible note investors, assuming broker-dealer rules only bite on equity sales. That assumption is wrong.
Paying transaction-based compensation – a cut of the money raised – to someone who is not a registered broker-dealer creates broker-dealer registration risk. It does not matter that the security is a note. What matters is that someone is being paid based on capital raised in a securities transaction.
That exposure runs both ways. The finder can face registration problems, and the issuer can face its own regulatory and rescission risk for using an unregistered person to sell securities.
If you need help raising the note capital, the clean path is to work with a registered broker-dealer or to structure any relationship so the compensation is not tied to the amount raised. Do not paper over a percentage-of-capital arrangement and hope the “it’s only debt” label protects you. It will not.
Integrating the Note into Your Legal Package
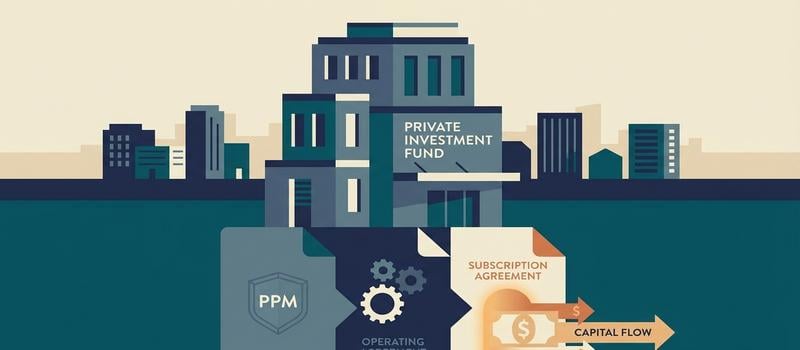
A convertible note is not a standalone document. It works only when it is written to match your Operating Agreement and your subscription documents, so the conversion actually functions when it triggers.
Think of the note as one piece of the legal package, not the whole deal. It helps structure the offering, but it depends on the other documents to do its job.
Aligning the Operating Agreement
The Operating Agreement has to authorize the note before the note means anything. If the agreement does not give the manager the power to issue convertible debt, you have a promise on paper with no mechanism behind it.
So the Operating Agreement needs to do two things. First, it must explicitly authorize the manager to issue convertible debt on the terms in the note. Second, it must accommodate the future dilution of the other members when that debt converts into membership interests.
Here is the practical failure point. A sponsor signs a note promising a $200,000 balance converts into a 2% GP interest, but the Operating Agreement never contemplates new members joining that way. When conversion time comes, the cap table does not reconcile, and now you are amending documents and asking existing investors to agree to something they never signed up for. That is an avoidable dispute.
A properly drafted note supports the legal package because it is written in the same language as the entity documents. The conversion terms in the note, the admission mechanics in the Operating Agreement, and the entry terms in the Subscription Agreement all need to describe the same event the same way.
Building that cohesive structure is where experienced counsel matters. This is the kind of interlocking drafting that legal services for real estate syndication sponsors are built to handle, because the risk is not in any single document. It is in the gaps between them.
The takeaway is simple. Draft the note, the Operating Agreement, and the subscription documents as one connected package, and you preserve your flexibility to actually execute the conversion when the time comes. Draft them in isolation, and you back yourself into a corner you do not need.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.