Why ‘Investor Benefits’ Are Structural, Not Just Marketing Material
A sponsor should view the benefits of a syndication as things the legal structure produces, not things the marketing says. That is the whole difference between how you read a deal and how a retail investor reads one.
An investor sees “passive income” and hears a promise. You need to see the same words and ask what document actually makes that income passive, who has control, and what happens if the cash is not there.
The benefits that sell a syndication – passivity, limited liability, access to bigger assets – are not features you announce. They are outcomes the Private Placement Memorandum, the Operating Agreement, and your Regulation D exemption create when they are drafted and operated correctly. Get the structure right and the benefits exist. Skip the structure and no amount of pitch language puts them back. This is the core of what proper legal services for real estate syndication sponsors actually deliver – not marketing polish, but the legal architecture that makes the pitch true.
The Danger of the Retail Hype Model
Most sponsors research how to pitch by reading what other people already wrote, and most of what is out there is retail hype.
They pull language from broker-dealer platforms built for a different regulatory posture, or worse, from late-night real estate gurus selling a course. Then they paste that language into their own materials and assume it is safe because everyone else uses it.
It is not safe. Phrases like “guaranteed passive income,” “predictable returns,” or “risk-free arbitrage” run straight into the SEC’s anti-fraud rules. Real estate carries debt, and leverage cuts both ways. Anytime you say something is guaranteed or risk-free, you are making a statement you cannot back up, and that is exactly what the anti-fraud provisions exist to catch.
Here is the mental shift. A private placement under Regulation D is a security. It is a regulated financial instrument, not a consumer product you can market like a mattress or a meal kit. The consumer marketing playbook is the wrong playbook, and copying it creates a disclosure problem you do not need.
The Documents That Manufacture the Benefits
The Private Placement Memorandum and the Operating Agreement do more than write down the deal. They build the legal framework that makes the benefits real in the first place.
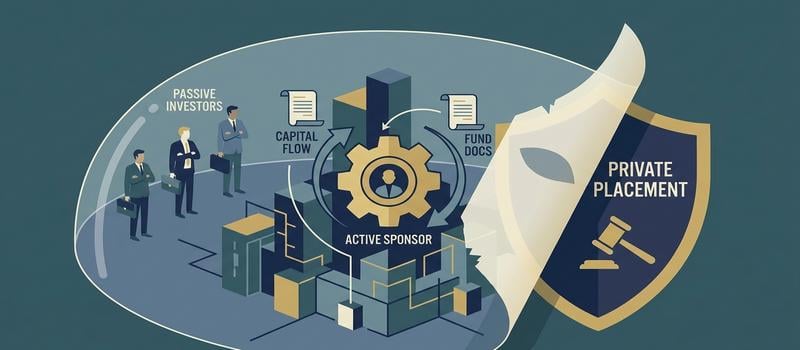
The Operating Agreement is what makes an investor passive – it grants the Manager sole operational authority and gives investors economic rights without control. The PPM is what discloses the risks and sets the terms so your Regulation D exemption holds. The subscription documents control how investors actually get in. These documents do not describe the benefits. They manufacture them.
That is why “staying compliant” is not a phrase I like. Compliance is not a shield you hold up after the fact. It supports the legal package only to the extent you actually execute the operational mechanics the documents require.
If your Operating Agreement says the Manager runs the deal but you let a large investor dictate decisions, the document says one thing and reality says another. In the real world, reality wins. The benefit you drafted evaporates because you did not operate the way the paper says you operate.
So the practical takeaway is simple. The documents help structure the benefits. Your day-to-day conduct is what keeps them intact.
The Legal Reality of “Passive Income”: Why the Howey Test Dictates Your Structure
Passivity is not just a selling point for busy professionals. It is a structural requirement that helps hold your Regulation D exemption together.
Here is the practical answer. If your investors are genuinely passive, you are selling a security, and you can structure that security under Reg D. If they are not passive, the whole legal theory of your offering starts to fall apart.
That is why “passive income” is not really a marketing feature. It is a design constraint you have to build around from day one.
Passivity Is What Makes It an Exempt Security
The Howey Test defines when an arrangement counts as an investment contract, which means a security. One of its core elements is that investors expect profits “solely from the efforts of others.”
In plain English, the investor puts in money and waits. You do the work. That expectation is what makes the interest a security in the first place, which is what lets you use Regulation D and Rule 506(b) or Rule 506(c).
Now the practical consequence. Say you are trying to close the round, and a large investor writing a $2 million check wants a seat at the table. They want approval rights over the budget, the hiring, and when you sell.
You can give them that. I just do not think you will like the problem it creates.
Once that investor is directing operations, they are no longer relying “solely on the efforts of others.” Their profits now depend partly on their own decisions. For that investor, and possibly for the offering, you have undercut the theory that this is a passive investment security.
That is not a wording problem. That is a structural problem. And it is exactly the kind of thing that gets messy when a deal goes sideways and someone’s lawyer starts looking for arguments.
Codifying the GP/LP Divide
The passive relationship does not enforce itself. Your legal package has to draw the line, and then you have to actually live by it.
The Operating Agreement or Limited Partnership Agreement gives the Manager, or General Partner, sole operational authority. The Manager decides on financing, capital expenditures, leasing, refinancing, and sale. The investors do not vote on the day-to-day.
What are the investors actually buying? Economic rights. They are buying the right to be paid according to the waterfall – their return of capital, their preferred return, their share of the upside – without a hand on the controls.
That split is the point. The Limited Partners get the economics. The Manager gets the authority. Keeping those two things separate is what supports the legal package you are relying on.
So when an investor asks for control as a condition of investing, the answer is not “sure, whatever closes the deal.” The answer is that control belongs to the Manager by design, and here is why that protects everyone in the deal, including them.
Structuring the Liability Shield: Protecting Investor Capital
Investors put money into a syndication partly because their downside is capped at the amount they write the check for. That cap is not marketing. It comes from the entity you form and how you actually run it.
For the sponsor, the practical point is this: the liability shield only holds if you keep the entity and the individual investors separate. Blur that line, and you can hand a court a reason to reach through the entity.
How the Entity Protects the LP
An investor in an LLC or LP is exposed up to their investment, and generally no further. If Susan puts $100,000 into the deal and the deal goes bad, she can lose that $100,000. What she does not lose is her house, her savings, or her business. Creditors of the venture do not get to reach her personal assets.
Compare that to owning the asset directly. If Susan buys a building in her own name and a tenant slips and falls, she is personally on the hook. If the loan defaults and there is a recourse guaranty, the lender can come after her directly. Direct ownership puts the individual in the line of fire.
The entity moves the risk off the individual and onto the pool of capital. That is the whole point of the LLC or LP wrapper. The investor gets economic exposure to the deal without personal exposure to the deal’s liabilities.
How Sponsors Accidentally Pierce the Shield
The shield protects the passive investor because the investor is passive. Let an investor step out of that role, and you start creating the argument that the separation was never real.
Here is where sponsors get into trouble. You let a large investor sign a vendor contract to get the deal closed. You let another one negotiate directly with the bank on the loan. Now that investor is acting like an operator, not a passive holder of economic rights.
That is a problem you do not need. Pulling an investor into operations does two things at once. It weakens the passivity that supports the securities exemption, and it gives a creditor a foothold to argue the investor should be treated as a principal rather than a shielded passive party.
If you want the liability shield to actually hold, keep control where the documents put it – with the Manager. Investors fund the deal and receive distributions under the waterfall. They do not sign the contracts, and they do not run the venture.
Pooling Capital for Scale: Why Syndications Beat Joint Ventures
The reason to use a syndication instead of partnering with a few wealthy friends comes down to control and math. A syndication pools fragmented capital into a single entity that one manager runs, which lets you acquire larger assets without asking ten partners to vote on every decision.
A joint venture works fine when you have two or three sophisticated partners who all expect a seat at the table. It stops working the moment you need real capital from people who do not want to run anything.
The Math of Institutional Scale
A larger asset usually behaves better than a stack of small ones. A single $20 million commercial property often carries better debt terms, lower relative operating costs, and stronger tenants than twenty separate $1 million buildings.
That is the practical benefit for the sponsor. You are buying into a tier of commercial real estate – or a private equity position, or a debt fund allocation – that no single investor in the group could reach on their own.
Pooling capital is what gets you there. Twenty investors writing $250,000 checks turn into a $5 million equity stack, and that stack is what lets you compete for the institutional-grade deal instead of the leftover ones.
The point is not that bigger is always better. The point is that scale changes what you can buy and how the lender treats you, and syndication is the mechanism that assembles the capital to reach it.
The Problem with “Too Many Cooks”
The real difference between a joint venture and a syndication is who gets to decide. In a JV with ten equal partners, every refinance, every sale, and every capital call runs through a vote.
That is a gridlock problem. If it were me, I would not want to chase down ten signatures every time the business plan needs a decision, and I definitely would not want one holdout partner able to block a refinance the deal actually needs.
A syndication solves that by centralizing authority in the Manager. The investors buy economic rights in the entity, and the Manager runs the operation. The Operating Agreement grants that authority directly, which supports the legal package and keeps the investors passive.
From your point of view, that means you treat the ten investors as capital, not as co-managers. They are entitled to be paid according to the waterfall, but they are not voting on whether to sign the loan documents.
From the investor’s point of view, that is usually what they signed up for. Most passive investors do not want operational control. They want to write the check, stay out of the day-to-day, and let the sponsor execute the plan they already decided to trust.
How to Discuss Targeted Returns and Tax Attributes Safely
Investors want cash flow and tax benefits. You cannot legally guarantee either one. The safer path is to state the targeted waterfall distribution clearly and tell investors to rely on their own CPA for tax outcomes.
This is where a lot of sponsors get into trouble by copying language they saw somewhere else. The problem is that most of that language treats projections as promises. Once you promise a result you do not control, you have moved from disclosure into a misrepresentation you do not need.
Targeted Returns vs. Guaranteed Wealth
Do not describe the deal as “predictable cash flow” or “risk-free.” There is debt on the asset, and leverage cuts both ways. When the deal underperforms, leverage makes the downside worse, not better. Calling that predictable is not accurate, and the SEC anti-fraud rules apply to what you say whether the offering is registered or not.
Use the language of a targeted preferred return instead. A preferred return is a priority of payment, not a promise that the cash will be there. It means the Issuer pays the investor first, up to the stated rate, before the sponsor participates in profits.
That distinction matters. “You get an 8% preferred return” tells the investor where they sit in line. “You will earn 8%” tells the investor they are guaranteed a number. The first is a description of the waterfall. The second is a promise you cannot keep.
So frame the number as a target and a priority. Then disclose the risk factors honestly in the PPM. Disclosure is how you handle this, not silence about the downside.
The ‘Pass-Through’ Tax Conversation
You can explain the general tax structure. LLC and LP structures are generally pass-through, so items like depreciation flow to the investor on a Schedule K-1 rather than being trapped at the entity level. That is a fair, accurate description of how the structure works.
What you should not do is promise the outcome. Do not tell investors the distributions will be tax-free, or that they can roll their interest into a 1031 exchange. The investor’s own tax profile controls the result, and you do not know their profile.
An investor with passive losses elsewhere gets a very different answer than an investor who has none. A 1031 exchange has its own strict requirements, and whether a given interest qualifies depends on facts you do not control.
So describe the mechanics of the structure, then send the investor to their own CPA for anything specific to their return. That keeps you on the right side of the line and puts the tax question where it belongs.
The Presentation Sequence: Character Before Spreadsheets
Present yourself before you present the deal. Establish who you are and why you can execute this specific business plan before you show a single projection. Investors commit to the person first and the numbers second, and sponsors who reverse that order lose commitments they should have won.
The structural benefits we have covered in this article are real. But they do not sell the deal on their own. The sequence in which you introduce them determines whether an investor leans in or backs away.
The ‘Numbers-First’ Pitching Trap
Leading with the return figure is the most common mistake sponsors make. They assume a strong projected IRR sells itself, so they open the conversation with a spreadsheet.
It does the opposite. A prospective investor who does not yet trust you does not see a 20% projected IRR as exciting. They see it as suspicious.
Sophisticated investors know that any number in a model can be made to say whatever the modeler wants. So when they see an aggressive projection from someone they do not know, they do not assume opportunity. They assume the underwriting is flawed, the assumptions are stretched, or both.
The number is not evidence. You are the evidence. The projection only becomes credible once the investor believes the person behind it can actually produce it.
Establishing Alignment of Interest
The order that works is character, then alignment, then metrics.
First, explain why you are the right person to execute this specific plan. Not your general resume – your fit for this deal. What have you done that is directly relevant to buying, operating, and exiting this kind of asset or business? This is what earns the right to be believed later.
Second, explain the alignment. Walk the investor through how you get paid. In a well-structured deal, the sponsor’s real money sits behind the investors in the waterfall – you earn your promote only after the investors receive their capital and their preferred return. That is not a marketing point. It is written into the Operating Agreement or LPA, and it tells the investor that your incentive is to make them money, not just to raise it.
Only after that foundation is set do you present the deal metrics and the structural benefits. The passivity, the liability shield, the scale, the targeted returns – all of it lands better once the investor already trusts the person delivering it.
In the real world, trust carries the projection. The projection does not carry the trust.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.