The Core Difference Is Not the Label, It Is the Bundle of Legal Rights
The fundamental difference between debt and equity is not “fixed interest” versus “sharing profits.” Debt is a strict contractual obligation backed by default remedies. Equity is an ownership interest subject to business risk and a distribution waterfall. When you issue debt, you owe a defined amount on a defined date, and missing it triggers consequences. When you issue equity, you owe your investors a share of what the venture actually produces, and if it produces nothing, you generally owe nothing.
That distinction runs through every part of the deal: who gets paid first, who controls decisions, what happens when cash runs short, and what an investor can do to you if things go wrong.
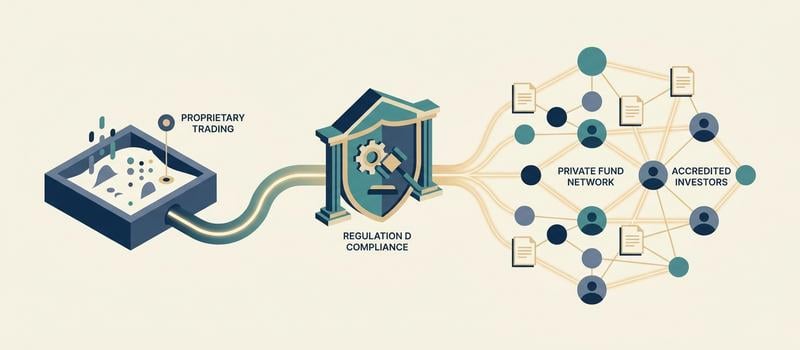
Regulation D does not decide any of that. It only decides how you are allowed to sell the security. The security type decides how the deal actually works.
The Compliance Envelope vs. The Legal Engine
Regulation D is the compliance envelope. Rule 506(b) lets you raise from accredited investors and a limited number of sophisticated non-accredited investors, but you cannot advertise or generally solicit. Rule 506(c) lets you advertise to the world, but every purchaser must be accredited, and you have to take reasonable steps to verify it – not just take their word for it.
Notice what neither rule says. Neither one tells you whether to sell debt or equity. That choice is yours, and it sits underneath the exemption.
You can run a debt offering under 506(b) or 506(c). You can run an equity offering under either one too. The exemption governs the marketing and the investor qualification. The security governs the economics, the control, and the remedies. Those are two separate decisions, and sponsors collapse them together all the time.
The Practical Misconception Held by Sponsors
Here is the mistake I see. A sponsor picks “debt” or “equity” based on what they think investors want to hear. Investors are nervous, so the sponsor promises a fixed 9% and calls it debt. Or investors want upside, so the sponsor hands out ownership without thinking about what that ownership actually lets them do.
Both moves ignore the mechanics that matter: who has priority, who has control, and what happens on default.
That gap does not hurt you while the money is coming in. It hurts you later, when the venture hits a cash crunch. If you called it debt, a missed payment is a legal default, and your investor may have the right to take the collateral or force the issuer into bankruptcy. If you called it equity, you may have given away voting rights that let your investors remove you as manager at the worst possible moment.
The label is not the point. The bundle of rights you actually granted is the point, and you should choose it deliberately.
The Capital Stack and Liquidation Priority
The clearest way to see the difference between debt and equity is the liquidation order. Debt holders are creditors, and they get paid before equity holders see a dollar. Equity holders sit at the bottom of the capital stack and absorb the first losses.
This is the ultimate downside distinction. Everything else – interest, distributions, voting, covenants – is a refinement of this basic ordering.
Understanding the Absolute Priority Rule
The capital stack is just the payment order when money gets distributed, and it runs top to bottom in a failure.
Senior secured lenders get paid first, up to the value of their collateral. Unsecured debt comes next. Then preferred equity. Then common equity gets whatever is left, which in a real liquidation is often nothing.
Here is why that ordering matters. A debt holder has a legal right to the proceeds. If the venture defaults, that creditor can enforce the note, claim the collateral, or push the issuer into a proceeding where a bankruptcy court honors the priority order.
An equity holder has no such right. Equity is an ownership interest, not a claim. The equity investor takes what is left after every creditor is satisfied, and if the assets do not cover the debt, the equity is wiped out.
So the practical answer is this: when you sell debt, you are telling that investor they stand ahead of the owners. When you sell equity, you are telling that investor they stand behind every creditor and eat the first losses.
Why Equity Demands a Higher Return
Because equity absorbs the first losses, equity investors demand a higher projected return. That is not greed. It is the price of standing at the bottom of the stack.
Nobody agrees to be last in line for the same yield a lender gets for being first. The equity investor is taking real business risk – the risk of total loss – so the projected upside has to be large enough to justify it.
This is where the sponsor has to think in tradeoffs. Debt is cheaper on paper because the return is fixed and lower, but it comes with a hard obligation to pay on schedule regardless of how the business is doing.
Equity is more expensive because you are giving away a share of the upside, but it flexes with the business. If cash is tight, you are not in default – you just have less to distribute.
From your point of view, the question is not which is “better.” It is which cost you would rather carry: the rigid obligation of debt, or the higher return demand of equity. That tradeoff drives most of the structuring decisions that follow.
Debt Mechanics: Strict Contracts, Covenants, and Default Triggers
When you issue a debt security, you sign up for a rigid contractual timeline. Missing a maturity date or breaking a covenant does not just pause returns. It triggers a default, and default remedies can cost you the asset.
The instrument here is usually a promissory note, often paired with a security agreement or a loan agreement. That note is a promise to pay a fixed amount, at a fixed rate, by a fixed date. It does not care about your business cycle.
Maturity Dates and Accrual Periods
Debt has a maturity date. On that date, the principal is legally due, whether or not the venture has the cash.
Interest accrues on its own schedule too. Whether you pay it monthly or let it accrue and balloon at the end, the clock runs regardless of how the operating company is performing.
Equity does not work this way. An equity investor rarely has a legal right to force a return of capital on a specific Tuesday. If the cash is not there, an equity distribution can be paused. A debt maturity cannot be wished away.
That is the core tradeoff. Debt is cheaper capital because it carries a hard promise, and the hard promise is exactly what can hurt you.
Operating Covenants and Sponsor Control
Debt investors do not sit at the table and vote on how you run the business. They govern by contract instead, through covenants.
Covenants come in two flavors. Affirmative covenants require you to do things, like deliver financial statements or maintain insurance. Negative covenants restrict what you can do without lender consent.
Negative covenants are where the sponsor feels the squeeze. A typical debt deal might bar you from taking on additional debt, cap executive or manager compensation, restrict distributions to equity, or limit how you can sell or encumber the collateral.
The reason is simple. A lender has no upside beyond its interest rate, so it protects itself by boxing in your downside behavior. From the investor’s point of view, covenants are the substitute for the voting rights they gave up by choosing debt.
From your point of view, this is a real loss of flexibility. You can live with it, but you need to read the covenants before you sign, because a covenant you cannot realistically comply with is a default waiting to happen.
Default Remedies and Foreclosure
Miss a payment, and you are in default. Break a covenant, and you are in default. There is no partial credit.
Once you are in default, the note usually gives the holder acceleration rights. That means the entire principal balance becomes due immediately, not just the payment you missed. A small stumble becomes the whole loan at once.
If the debt is secured, the holder can move against the collateral. That might mean foreclosing on the pledged assets, sweeping accounts, or taking control of the operating company’s property. If the debt is unsecured, the holder can sue on the note and, in a bad enough situation, push the issuer into bankruptcy.
This is the part sponsors underestimate. Equity investors who are unhappy can remove a manager or refuse to fund more capital. A debt holder in default can take the asset out from under you. That difference is the whole reason the choice between debt and equity is a structural decision, not a marketing one.
Conversion Features: Trading Creditor Rights for Equity Upside
A convertible note is debt with an option bolted on. The investor holds a real creditor position – fixed rate, maturity date, covenants, default remedies, all of it – right up until the conversion feature lets them trade that position for equity instead.
The practical logic is simple. Early on, the venture is unproven, so the investor wants the protection of debt: a defined return, a maturity date, and remedies if things go wrong. If the venture succeeds, the investor wants to have participated in the upside instead of just collecting interest. The conversion feature lets them have it both ways, but only one at a time. They are a creditor until the trigger hits, and an owner after.
The trigger is usually tied to a future priced equity round, a specified date, or a change of control, and it converts the note into membership or partnership interests at a set price, a discount, or a valuation cap. Get the trigger and the conversion price wrong, and you do not find out until the raise you were counting on either happens or does not.
Here is the drafting risk. Until conversion actually happens, you have to manage the instrument as debt – covenants, maturity, and all. If you treat it like equity because you expect it to convert, and it does not convert on schedule, you are suddenly in default on an obligation you were not tracking. I would draft the conversion mechanics as tightly as the promissory note itself, not as an afterthought.
Equity Mechanics: Manager Discretion, Voting Rights, and Waterfalls
Equity trades the rigid contract of debt for ownership mechanics. There is no promissory note and no maturity date. The relationship is governed by an Operating Agreement (or an LPA in a limited partnership), and that document defines the distribution waterfall, the manager’s discretion, and the investor’s voting rights.
That shift changes the sponsor’s job. With debt, you owe a fixed sum on a fixed date. With equity, you owe your investors a fair share of the upside and honest management, but you do not owe them their money back on a specific Tuesday.
Issuing Membership Interests, Not “Shares”
In a private capital raise, you are almost never issuing corporate stock. Sponsors in real estate, private equity, and operating companies typically use an LLC or an LP as the issuer.
So the investor is buying a membership interest in the LLC or a limited partnership interest in the LP. Not “shares.”
This is not just vocabulary. The interest is defined entirely by the Operating Agreement or LPA. There is no default corporate law setting the terms for you the way it would with stock. Whatever the document says the investor gets, that is what the investor gets.
The Distribution Waterfall vs. Strict Interest
Money flows to equity investors through a distribution waterfall, not a fixed interest payment. The waterfall is just the order in which available cash gets paid out – return of capital, preferred return, then the split between investors and the sponsor.
The key word is available. Equity distributions depend on cash flow and, in many deals, on the manager’s discretion to distribute rather than reserve. Even a preferred return is a priority in the waterfall, not a debt.
That is the practical difference. If you skip a debt payment, you are in default and the lender has remedies. If you pause an equity distribution, the preferred return usually just accrues and sits at the front of the line for the next distribution. Nobody can accelerate the loan or take the assets, because there is no loan.
But do not read that as a free pass. Missing a preferred return will not get your collateral seized, but the Operating Agreement can still make it hurt. It is common to see the sponsor’s fee suspended, or subordinated behind the accrued preferred, until the shortfall is caught up. Some agreements go further and give investors a removal vote if the preferred goes unpaid past a set number of periods. There is no foreclosure, but there is real consequence, and you should know exactly what it is before you sign the document.
From the sponsor’s point of view, that is breathing room. From the investor’s point of view, it is business risk. Both need to understand it going in, which is why the Operating Agreement has to say clearly how the preferred accrues and compounds, and what happens to the manager if it does not get paid.
Voting Rights and Major Decisions
Equity investors are part owners, so they usually get a vote on major decisions – selling the asset, dissolving the entity, adding new capital, or removing the manager for cause. That is the trade-off. You gave up the fixed obligation of debt, but you took on partners who have a say in the big moves.
The goal in drafting is balance. You want the manager to run the day-to-day business without calling a vote every time a decision comes up. You also want investors protected on the decisions that actually affect their money.
A well-drafted Operating Agreement handles this by reserving broad operating discretion to the manager and limiting investor votes to a short list of genuinely major decisions. Do not put yourself in a box by requiring investor approval for ordinary operating choices. And do not strip investors of the votes they reasonably expect, because that becomes a disclosure and trust problem long before it becomes a legal one.
The Hybrid Zone: Preferred Equity and Substance Over Form
Sponsors often ask if they can call a security “preferred equity” to sidestep debt restrictions while still promising investors a fixed return. The answer is no. Courts, the IRS, and bankruptcy trustees look at what the instrument actually does, not what you named it. If your “preferred equity” has a mandatory maturity date and the ability to foreclose, someone can argue it is really debt.
What Preferred Equity Actually Does
Preferred equity is a tool of priority, not a guarantee. It gives the investor the right to be paid ahead of common equity in the distribution waterfall, and usually ahead of common on liquidation too.
That is the whole point of the “preferred” label. The investor sits closer to the front of the line than common, but still behind every creditor.
What preferred equity does not do is turn the investment into a loan. It is still an ownership interest. It is still subject to business risk. If the venture does not generate cash, the preferred return accrues, but nobody has breached a contract by failing to pay it.
That is the trade. The investor accepts equity risk in exchange for priority. If you want to give them a hard payment obligation instead, you are describing debt, and you should issue debt.
The Risk of Recharacterization
The danger is dressing up debt as equity to get the best of both worlds. It does not work, and it can create problems you do not need.
Here is the pattern that gets sponsors in trouble. You call it preferred equity, but you also give it a mandatory maturity date, a fixed rate that must be paid regardless of cash flow, and a right to foreclose or take control on nonpayment. At that point the instrument walks and talks like a loan.
When it does, a bankruptcy court may treat the holder as a creditor. A senior lender may argue your “preferred equity” is actually subordinated debt that violates their loan covenants. And the IRS may recharacterize the instrument for tax purposes, which changes how the payments are treated and can undo the tax result you were counting on.
I am not going to tell you how any specific hybrid gets taxed. That is a question for a qualified CPA, and the answer depends on the exact terms and the facts. The point is narrower: the more debt-like features you bolt onto preferred equity, the more you risk having it treated as debt when it matters most.
So decide what you actually want. If you want fixed, mandatory, enforceable payments, issue debt and accept the covenants and default remedies that come with it. If you want priority without a hard obligation, issue real preferred equity and keep the mandatory-repayment features out. Trying to have both is how you end up with a security that gets reclassified against you.
How Your Choice Rewrites the Offering Documents
Once you pick debt or equity, the drafting is largely decided for you. The security you sell dictates the legal structure for a business capital raise, and that structure controls what the documents have to say.
A debt offering points the Private Placement Memorandum at default and collateral. An equity offering points it at dilution, manager reliance, and illiquidity. Same Regulation D envelope, different engine, different disclosure.
The documents themselves shift too. A debt deal centers on the promissory note and its covenants. An equity deal centers on the Operating Agreement, PPM, and Subscription Agreement that define the waterfall, voting, and manager authority.
Drafting the Risk Factors in the PPM
The risk factors in a debt PPM and an equity PPM are not interchangeable. They describe different ways the investor can get hurt.
A debt PPM has to disclose the things that threaten repayment. That means interest coverage – whether the venture actually generates enough cash to service the note – subordination to any senior lender who gets paid first, and what happens on default, including acceleration and loss of the collateral.
An equity PPM has to disclose the things that come with ownership. That means the risk of total loss, the lack of voting control on most decisions, reliance on the manager to execute, illiquidity because there is no easy way out, and distributions that are not guaranteed and may never come.
If you copy debt risk factors into an equity deal, or the reverse, the PPM stops matching the security. That is a disclosure problem you do not need.
Matching the Business Reality to the Legal Architecture
Before you choose, map your realistic cash flow. Not the pitch-deck version – the version where a slow quarter shows up.
Debt only works if the venture can make the payments on the schedule the note demands. Force a debt structure onto a business with lumpy or uncertain cash flow, and you are not raising capital, you are scheduling your own default.
Equity solves that timing problem, but it is expensive. If you only need cash to bridge a short-term gap, giving away permanent ownership to get it is a bad trade.
So the sequence is: figure out how the money actually comes in, then choose the security that survives that reality, then draft to match. Do it in that order and the documents write themselves. Do it backwards and you are papering over a structure the business cannot support.

Tilden Moschetti, Esq., is a highly sought-after syndication attorney with nearly two decades of experience. His clientele ranges from real estate developers and startups to established businesses and private equity funds. Tilden’s expertise in syndication law comes not only from his knowledge of syndication and securities law but from real, hands-on experience as an active syndicator himself in every real estate product type and nearly all markets in the US. His knowledge and experience set him apart and established him as the Reg D legal services leader.